
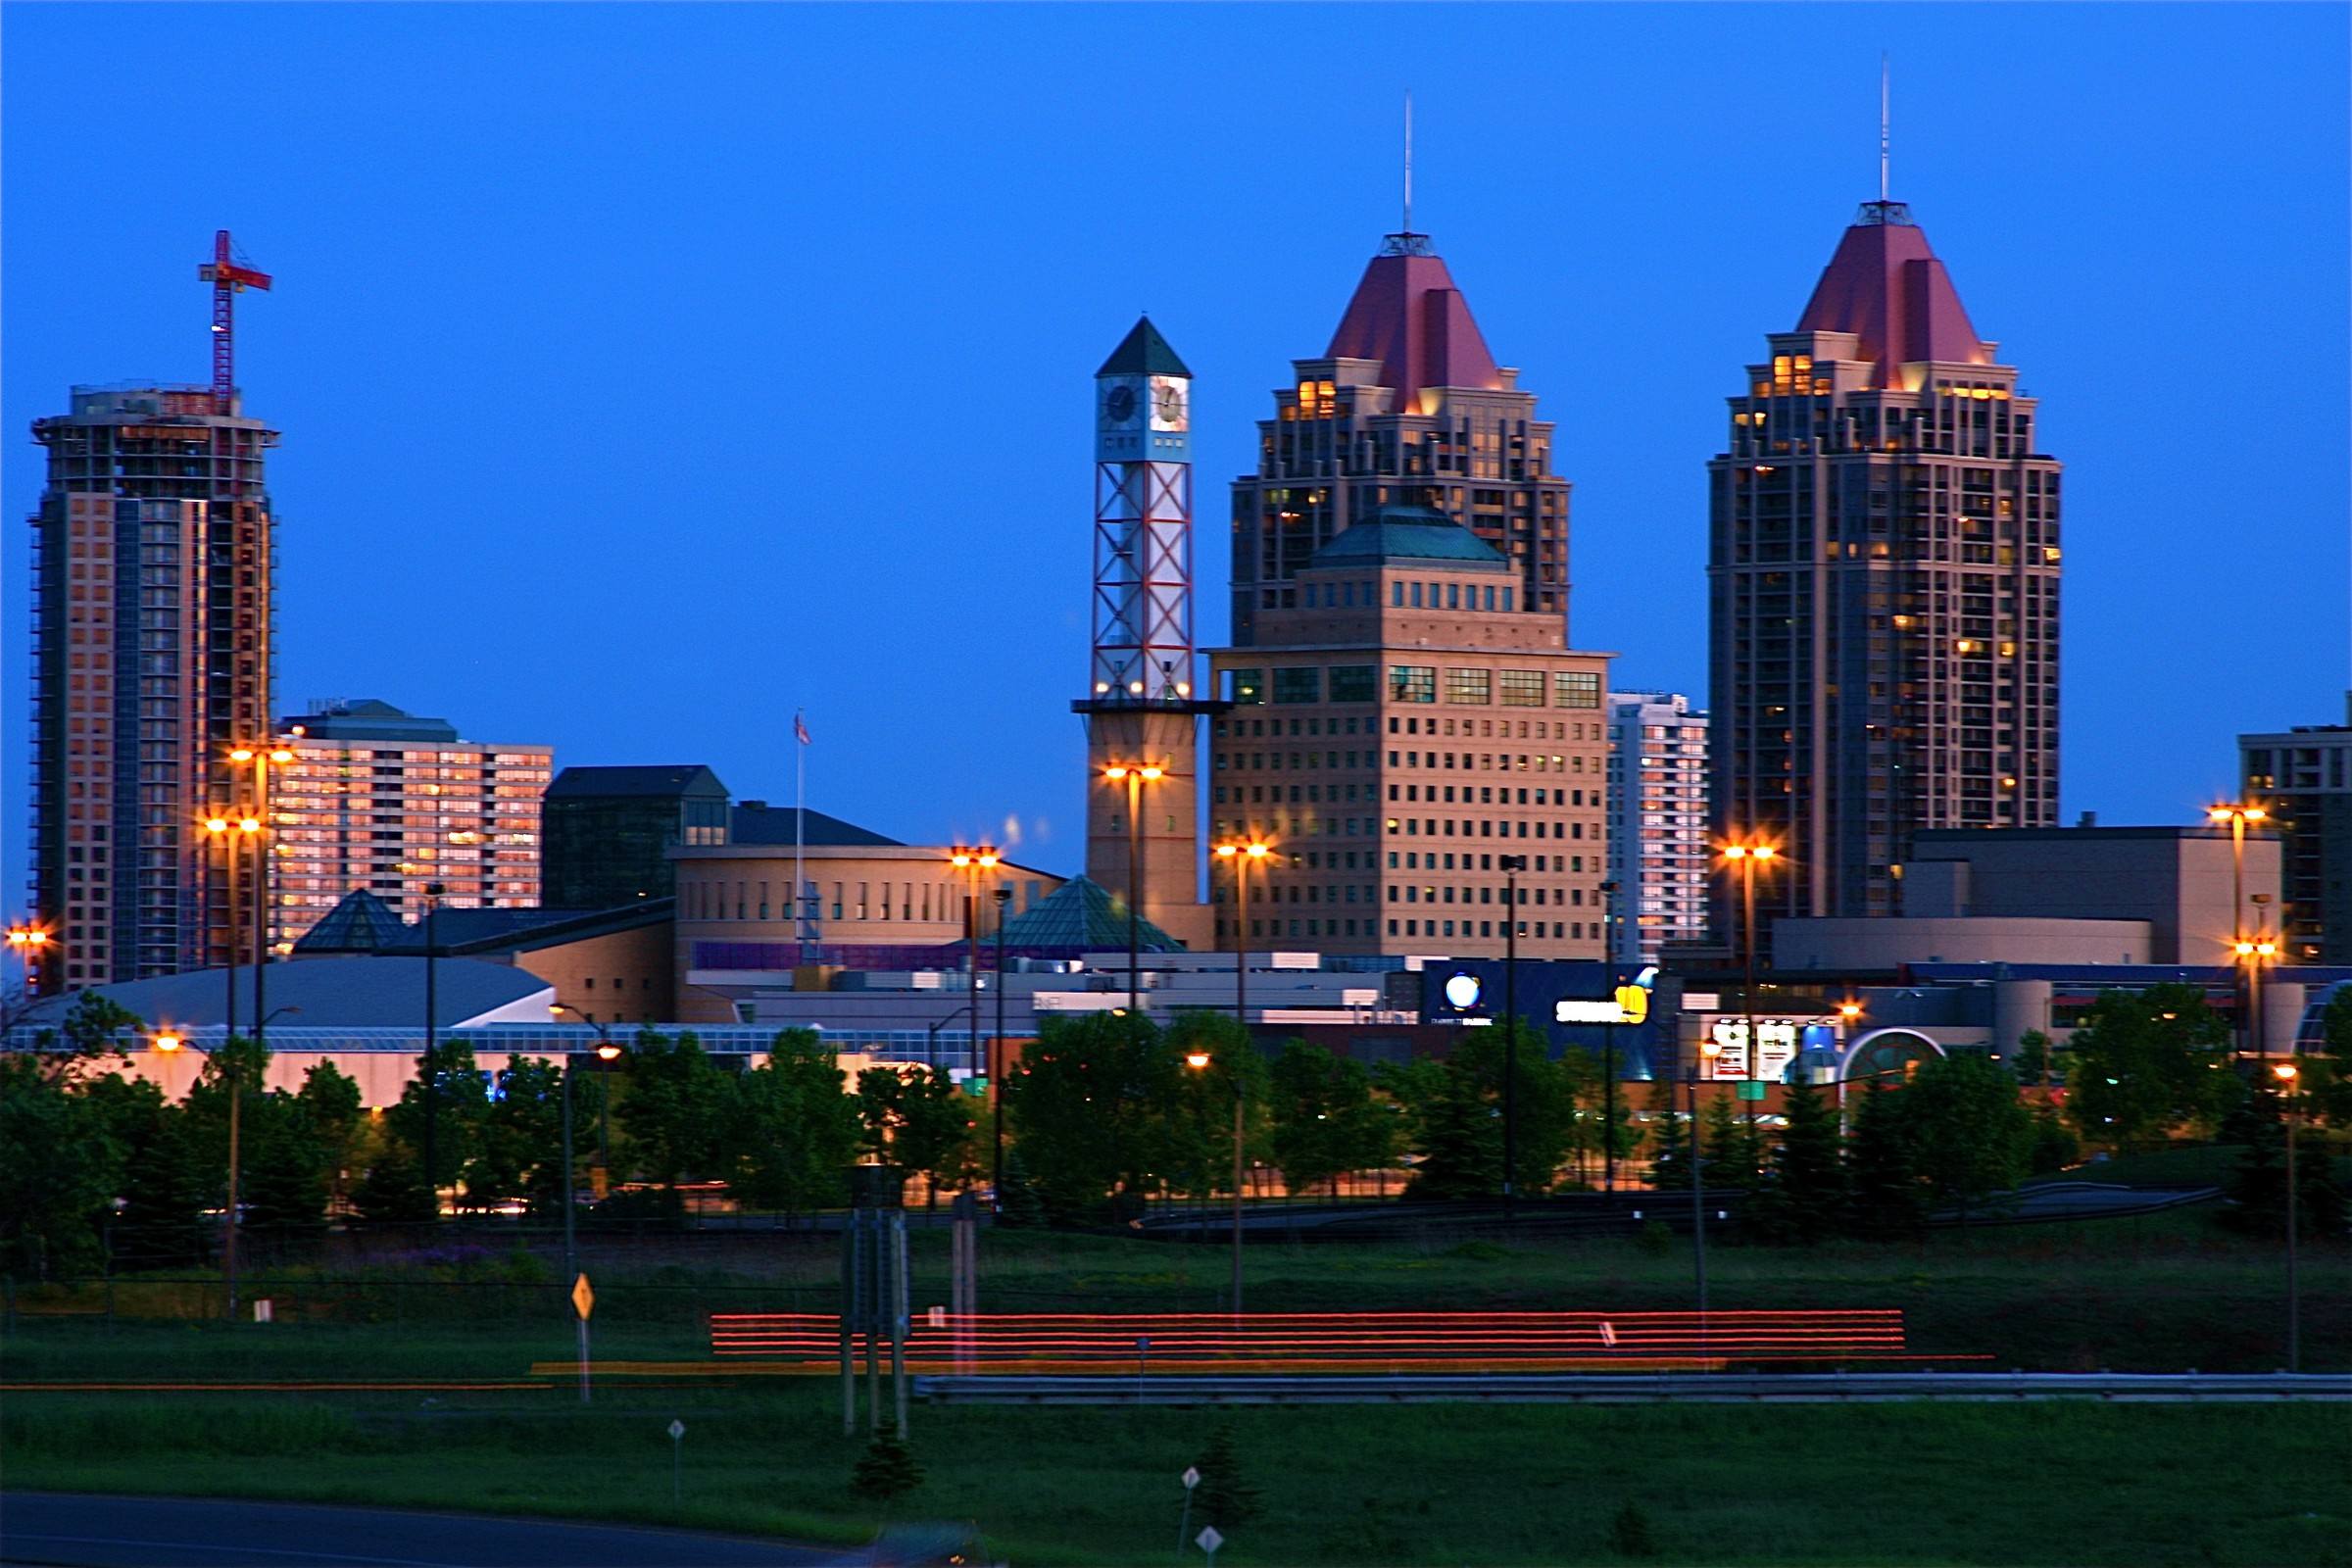

- Average price, Mississauga, all property types
- $927,521As of October 2026.Source
- Median price, Mississauga, all property types
- $843,000As of October 2026.Source
- Months of inventory, Mississauga (TRREB trend)
- 4.9As of October 2026.Source
- Population of Mississauga, and change since 2016
- 717,961 (down 0.5%)As of 2021 Census.Source
On this page
Mississauga sits between two much-discussed markets. Toronto’s prices make headlines, and Brampton’s are lower. The result is a city where owners usually have solid equity and still hit a ceiling sooner than they expect.
Mississauga’s $84,521 gap between average and median
TRREB’s October 2026 Market Watch records 508 Mississauga sales at an average of $927,521 and a median of $843,000. The $84,521 gap between those two numbers says a smaller group of expensive homes lifts the average, so the median is the better picture of a typical sale. Year to date, ten months of 2026, the average is $949,769 and the median $865,000, so October came in a little below the year so far.
Homes took an average of 35 days to sell and went for about 97% of asking. TRREB’s trend measure shows 4.9 months of inventory in the city, the same figure as Peel Region as a whole. That is a market where buyers have choice but homes still sell, which is the condition a second mortgage lender wants to see behind its security.
In Mississauga the 2021 Census found 717,961 people, a fall of 0.5% from 2016. Ontario as a whole grew 5.8% over the same five years, so Mississauga went against the provincial trend. That is a fact about the census count, not a forecast for your street.
Why Mississauga equity and room differ
Equity is what the home is worth minus what you owe. Room is smaller: the limit the Financial Consumer Agency of Canada describes is 80% of appraised value minus your mortgage balance, so the lender leaves a 20% cushion.
The two examples above use Mississauga’s own median and average. A median-priced owner with a modest first mortgage has $154,400 of room. An owner at the average price with a $700,000 balance has $42,017, and a $120,000 wish does not fit. The calculator on the second mortgage calculator page lets you swap in your own balance and value.
If you bought or renewed at a high price, the second example may be closer to your position than the first.
Property type moves the number more than the city does
TRREB’s October 2026 table splits Mississauga by type. The 200 detached sales averaged $1,326,044 with a median of $1,150,000, which is $398,523 above the all-type average. The 128 condo apartment sales averaged $504,685, which is $422,836 below it. The city average of $927,521 therefore describes almost nobody’s home.
Mississauga was also half of Peel Region’s activity: 508 of the region’s 1,017 sales, against 435 in Brampton. Peel’s own average was $898,431, so Mississauga sits above its region. Before you borrow, find the figure for your own type of home, not the one for the city.
Taxes and fees: why Toronto’s extra tax does not apply
Ontario’s land transfer tax applies when property is bought. The province’s website mentions a second, municipal land transfer tax only for Toronto, and Mississauga is not Toronto. In any case, a second mortgage on a home you already own is not a purchase, and we found no land transfer tax line for it.
What you can expect to pay instead: the lender’s fee, a broker fee if a licensed agent arranges the loan, a lawyer, an appraisal, and the registration fee covered on the Ontario page. Ask for every figure in writing before you sign anything.
Where Mississauga sits in Ontario’s arrears picture
CMHC’s October 27, 2026 release says Ontario’s arrears rate, meaning payments 90 or more days late, reached 0.32% in the second quarter of 2026 and is expected to keep rising through mid-2027. It names the Greater Toronto and Hamilton Area as one of two regions where the rise is concentrated. Mississauga is part of that area. CMHC does not give a figure for the city.
CMHC also says the largest renewal shock has probably passed. Still, if a renewal is the reason you are looking at a second mortgage, price a renewal with your current lender and a bank refinance first. Our HELOC or second mortgage page lays out where a bank line may be enough, and the debt consolidation page shows how fees can eat a first year of savings.
Licence numbers and the FSRA register
A mortgage agent or broker in Ontario must hold an FSRA licence, and for private lenders the person needs Level 2 or a broker licence. Look up the number on FSRA’s register before you hand over documents.
When your Mississauga figures are ready, ask a licensed professional to go through them. Nearby, see how Brampton and Oakville compare.
A Mississauga home at the October 2026 median, with a $60,000 loan
The $843,000 value is TRREB's October 2026 median price for Mississauga, all property types, used as a stand-in for an appraisal. The $520,000 first mortgage and $60,000 loan are made up. The 80% ceiling is the one the Financial Consumer Agency of Canada describes.
- Home value used
- $843,000
- Equity before the loan
- $323,000
- 80% of the home value
- $674,400
- Combined loan-to-value with the loan
- 68.8%
- Room under an 80% ceiling before the loan
- $154,400
$843,000 minus $520,000
$843,000 times 0.8
$580,000 owed on $843,000
A Mississauga home at the October 2026 average, with a $120,000 loan
The $927,521 value is TRREB's October 2026 average price for Mississauga, all property types, as a stand-in for an appraisal. The $700,000 first mortgage and $120,000 loan are made up.
- Home value used
- $927,521
- 80% of the home value
- $742,017
- Room under the ceiling
- $42,017
- Loan wanted
- $120,000
- Combined loan-to-value if the full loan were made
- 88.4%
- Amount the loan exceeds the room by
- $77,983
$927,521 times 0.8, rounded
$742,017 minus $700,000
$820,000 owed on $927,521
Questions people ask
Is a Mississauga detached house more likely to qualify than a condo?
Not necessarily. In October 2026 detached sales averaged $1,326,044 and condo apartments $504,685, so the dollars of room differ a lot. Lenders still judge the building or lot, the first mortgage and your plan to repay. Ask each which property types it accepts and what it charges.
Why does Mississauga's population matter to a lender?
It does not decide your file, but it hints at demand. The 2021 Census counted 717,961 people, down 0.5% from 2016. A lender still values your own home with its own appraisal.
How long does a home take to sell in Mississauga?
TRREB's October 2026 table shows an average of 35 days from listing to sale for Mississauga, and homes sold at about 97% of list price. Lenders care because they want a way out if a loan goes bad. Your own home may sell faster or slower.
Does moving from Toronto's rules to Mississauga's change my closing costs?
Ontario's website mentions a separate municipal land transfer tax only for Toronto, and that tax applies to purchases anyway. For a second mortgage on a Mississauga home you own, expect lender and broker fees, legal costs, an appraisal and a registration fee.
Sources
- TRREB: Market Watch, October 2026, 2026-10
- Statistics Canada: Focus on Geography Series, 2021 Census, Mississauga
- Financial Consumer Agency of Canada: Borrowing against your home equity
- Ontario.ca: Land transfer tax
- CMHC: Ontario mortgage arrears expected to rise through mid-2027, October 27, 2026, 2026-10-27