
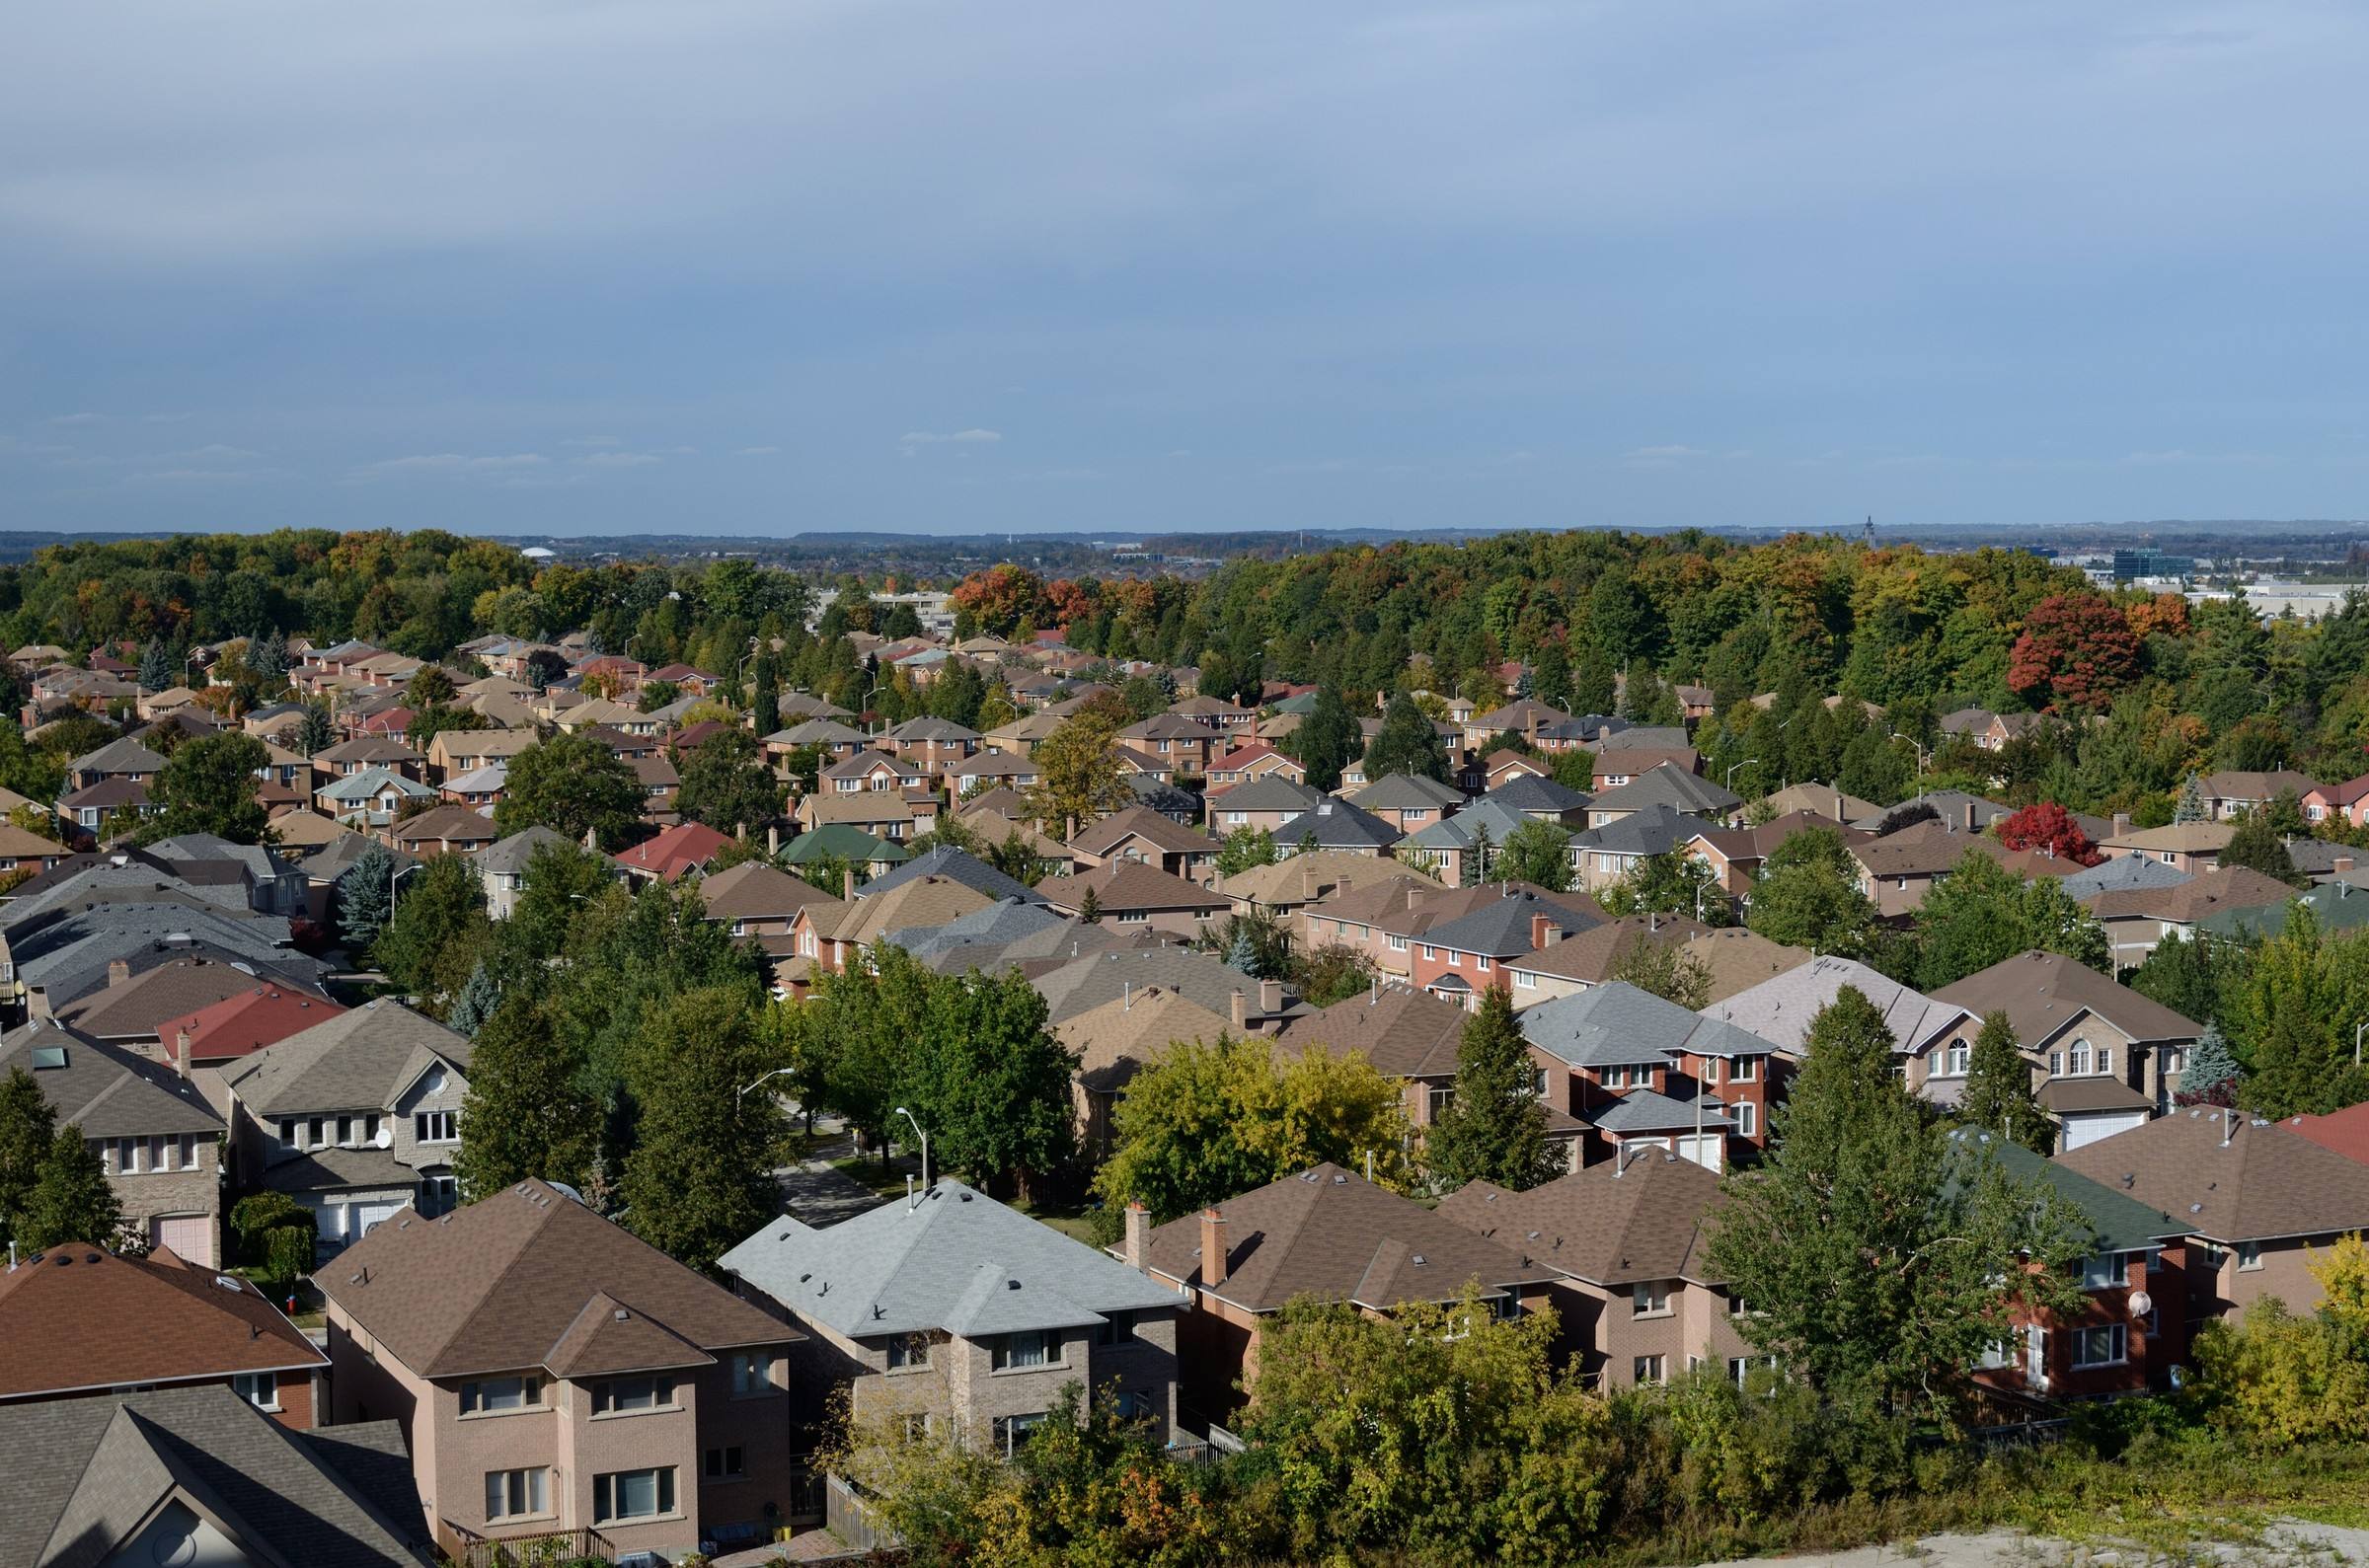
- Median price, Richmond Hill, all property types
- $1,150,000As of October 2026.Source
- Average detached price, Richmond Hill
- $1,521,374As of October 2026.Source
- Months of inventory, Richmond Hill (TRREB trend)
- 5.5As of October 2026.Source
- Population of Richmond Hill
- 202,022As of 2021 Census.Source
On this page
Richmond Hill, in York Region north of Toronto, counted 202,022 residents in 2021. Prices here are high, and that shapes what a second mortgage lender sees.
Detached, condo and the gap in between
TRREB’s October 2026 Market Watch shows Richmond Hill at a median of $1,150,000 and an average of $1,193,772 across all property types, with 185 sales and homes selling at about 98% of their list price after an average of 31 days. Detached homes averaged $1,521,374 on 105 sales. Those numbers sit well above the Durham Region average of $793,024 the same month.
The spread inside the town matters more than the headline. A detached owner and a condo owner live in different markets, and a lender prices each separately. A lender that is comfortable with a detached home on its own lot may ask more questions about a unit in a building.
What a lender can offer is not what you own
Two ceilings apply, both described by the Financial Consumer Agency of Canada: a second mortgage up to 80% of the appraised value minus the mortgage balance, and a HELOC up to 65% of value. The two examples above show it with Richmond Hill figures. The detached case leaves $367,099 of room. The median-priced case leaves $450,000 of equity but only $47,500 under a HELOC ceiling, and $220,000 under the second mortgage ceiling.
Before you decide on a loan size, price the fees too. Appraisal, legal fees, title insurance and lender or broker fees come off what you receive. The calculator lets you test an amount against your own value and balance. If you want a cheaper line first, read HELOC or second mortgage.
Inventory is higher here than in Durham
October’s trend figure of 5.5 months of inventory in Richmond Hill is higher than TRREB showed for nearby York and Durham towns. Whitby came in at 3.0, Ajax 3.1, Pickering 3.8 and Newmarket 4.1. In plain terms, Richmond Hill had more homes for sale relative to sales, so a buyer has options. A private lender thinking about the worst case, a forced sale, sees a market where a home may take longer to sell than in a tighter town.
None of this predicts your home’s value. It does explain why two lenders may offer different amounts on similar homes, and why the appraisal matters.
Costs and what they do not include
Ontario’s land transfer tax applies when you buy, not when you register a second mortgage on a home you already own. The Ontario page sets out the brackets, the registration fee and the legal costs. We have not found a Richmond Hill tax line for a second mortgage, and your lawyer will confirm the fees on your own charge.
Allow for a lender fee, a broker fee, legal work, an appraisal and the registration charge. On a $100,000 loan, those costs are a real slice of the first year’s expense, which the home equity loan page goes through.
The arrears picture around Richmond Hill
CMHC’s October 2026 release put Ontario arrears at 0.32% in the second quarter of 2026 and said it expects them to keep rising through mid-2027. It named the Greater Toronto and Hamilton Area and Southwestern Ontario as the places where the pressure is concentrated, and tied it to trade tension hitting manufacturing, job uncertainty and softer housing conditions. The same release said the largest renewal shock has likely passed, and that delinquencies on auto loans, credit cards and lines of credit are rising, which can show up before mortgage arrears.
Richmond Hill is inside that wider area, though the release does not single it out. If you have credit card or line of credit balances growing, that is the early sign CMHC points to. Consolidating them into a second mortgage can lower the monthly bill, and it can also put your home behind a new loan, so read the equity takeout refinance page and the bank and B-lender second mortgage page before you commit.
Checking who holds the licence
In Ontario, only a Level 2 agent or a broker should be dealing with private lenders for you, and the regulator’s register will show the licence number. Once your Richmond Hill numbers are down on paper, the options form is a way to get them reviewed.
A Richmond Hill detached home at the October 2026 average price
The $1,521,374 value is TRREB's October 2026 average detached price in Richmond Hill, used as a stand-in for an appraisal. The $850,000 first mortgage and the $150,000 new loan are made up. The 80% ceiling is the one the Financial Consumer Agency of Canada gives for second mortgages.
- Home value used
- $1,521,374
- Owed on the first mortgage
- $850,000
- 80% of the home value
- $1,217,099
- Combined loan-to-value with a $150,000 loan
- 65.7%
- Room under an 80% ceiling before the loan
- $367,099
$1,521,374 x 0.8
$1,000,000 divided by $1,521,374
A Richmond Hill home at the October 2026 median, three ceilings
The $1,150,000 value is TRREB's October 2026 median price for all property types in Richmond Hill, used as a stand-in. The $700,000 first mortgage and the $100,000 new loan are made up. The FCAC gives 65% of value as the HELOC limit and 80% of value minus the balance for a second mortgage.
- Equity before any new loan
- $450,000
- 65% HELOC limit minus first mortgage
- $47,500
- 80% second mortgage limit minus first mortgage
- $220,000
- Combined loan-to-value with a $100,000 second mortgage
- 69.6%
- Room left after a $100,000 second mortgage
- $120,000
$1,150,000 minus $700,000
$747,500 minus $700,000
$920,000 minus $700,000
$800,000 divided by $1,150,000
Questions people ask
Does a Richmond Hill detached home give more borrowing room than a condo?
Usually, because the same percentage ceiling applies to a bigger number. TRREB's October 2026 data put the average Richmond Hill detached price at $1,521,374. Lenders still look at the building or lot, the first mortgage and the plan to repay, so ask any lender about your specific property.
How many months of homes were for sale in Richmond Hill in October 2026?
TRREB's trend figure was 5.5 months of inventory, higher than the 4.1 shown for Newmarket and well above the 3.0 for Whitby the same month. More supply means buyers have more choice, which a lender weighs when it thinks about resale.
Do I qualify for a second mortgage if my income is high but my first mortgage is large?
Income helps, but the ceiling is set by value minus what you owe. A large first mortgage shrinks the room whatever you earn. Private lenders lean more on the property, while banks lean more on income and credit.
Is Richmond Hill part of the area where mortgage arrears are rising?
CMHC's October 2026 release said arrears pressure in Ontario is concentrated in the Greater Toronto and Hamilton Area and Southwestern Ontario. It did not name Richmond Hill. Arrears were 0.32% provincially in the second quarter of 2026.
What should I bring to a lender for a Richmond Hill home?
Bring the current mortgage statement, the latest property tax bill, proof of insurance, and a list of the debts you want to deal with. If the home is a condo, bring the status certificate. The lender will order its own appraisal.
Sources
- TRREB: Market Watch, October 2026, 2026-10
- Statistics Canada: Census Profile, 2021 Census of Population, Richmond Hill (census subdivision)
- Financial Consumer Agency of Canada: Borrowing against your home equity
- CMHC: Ontario mortgage arrears expected to rise through mid-2027, October 27, 2026, 2026-10-27