

- Single-family median price, Island of Montreal
- $812,000As of Q3 2026.Source
- Condominium median price, Island of Montreal
- $477,000As of Q3 2026.Source
- Residential sales, Montreal CMA
- 3,252 (down 18%)As of October 2026.Source
- Population of the City of Montreal
- 1,762,949As of 2021 Census.Source
On this page
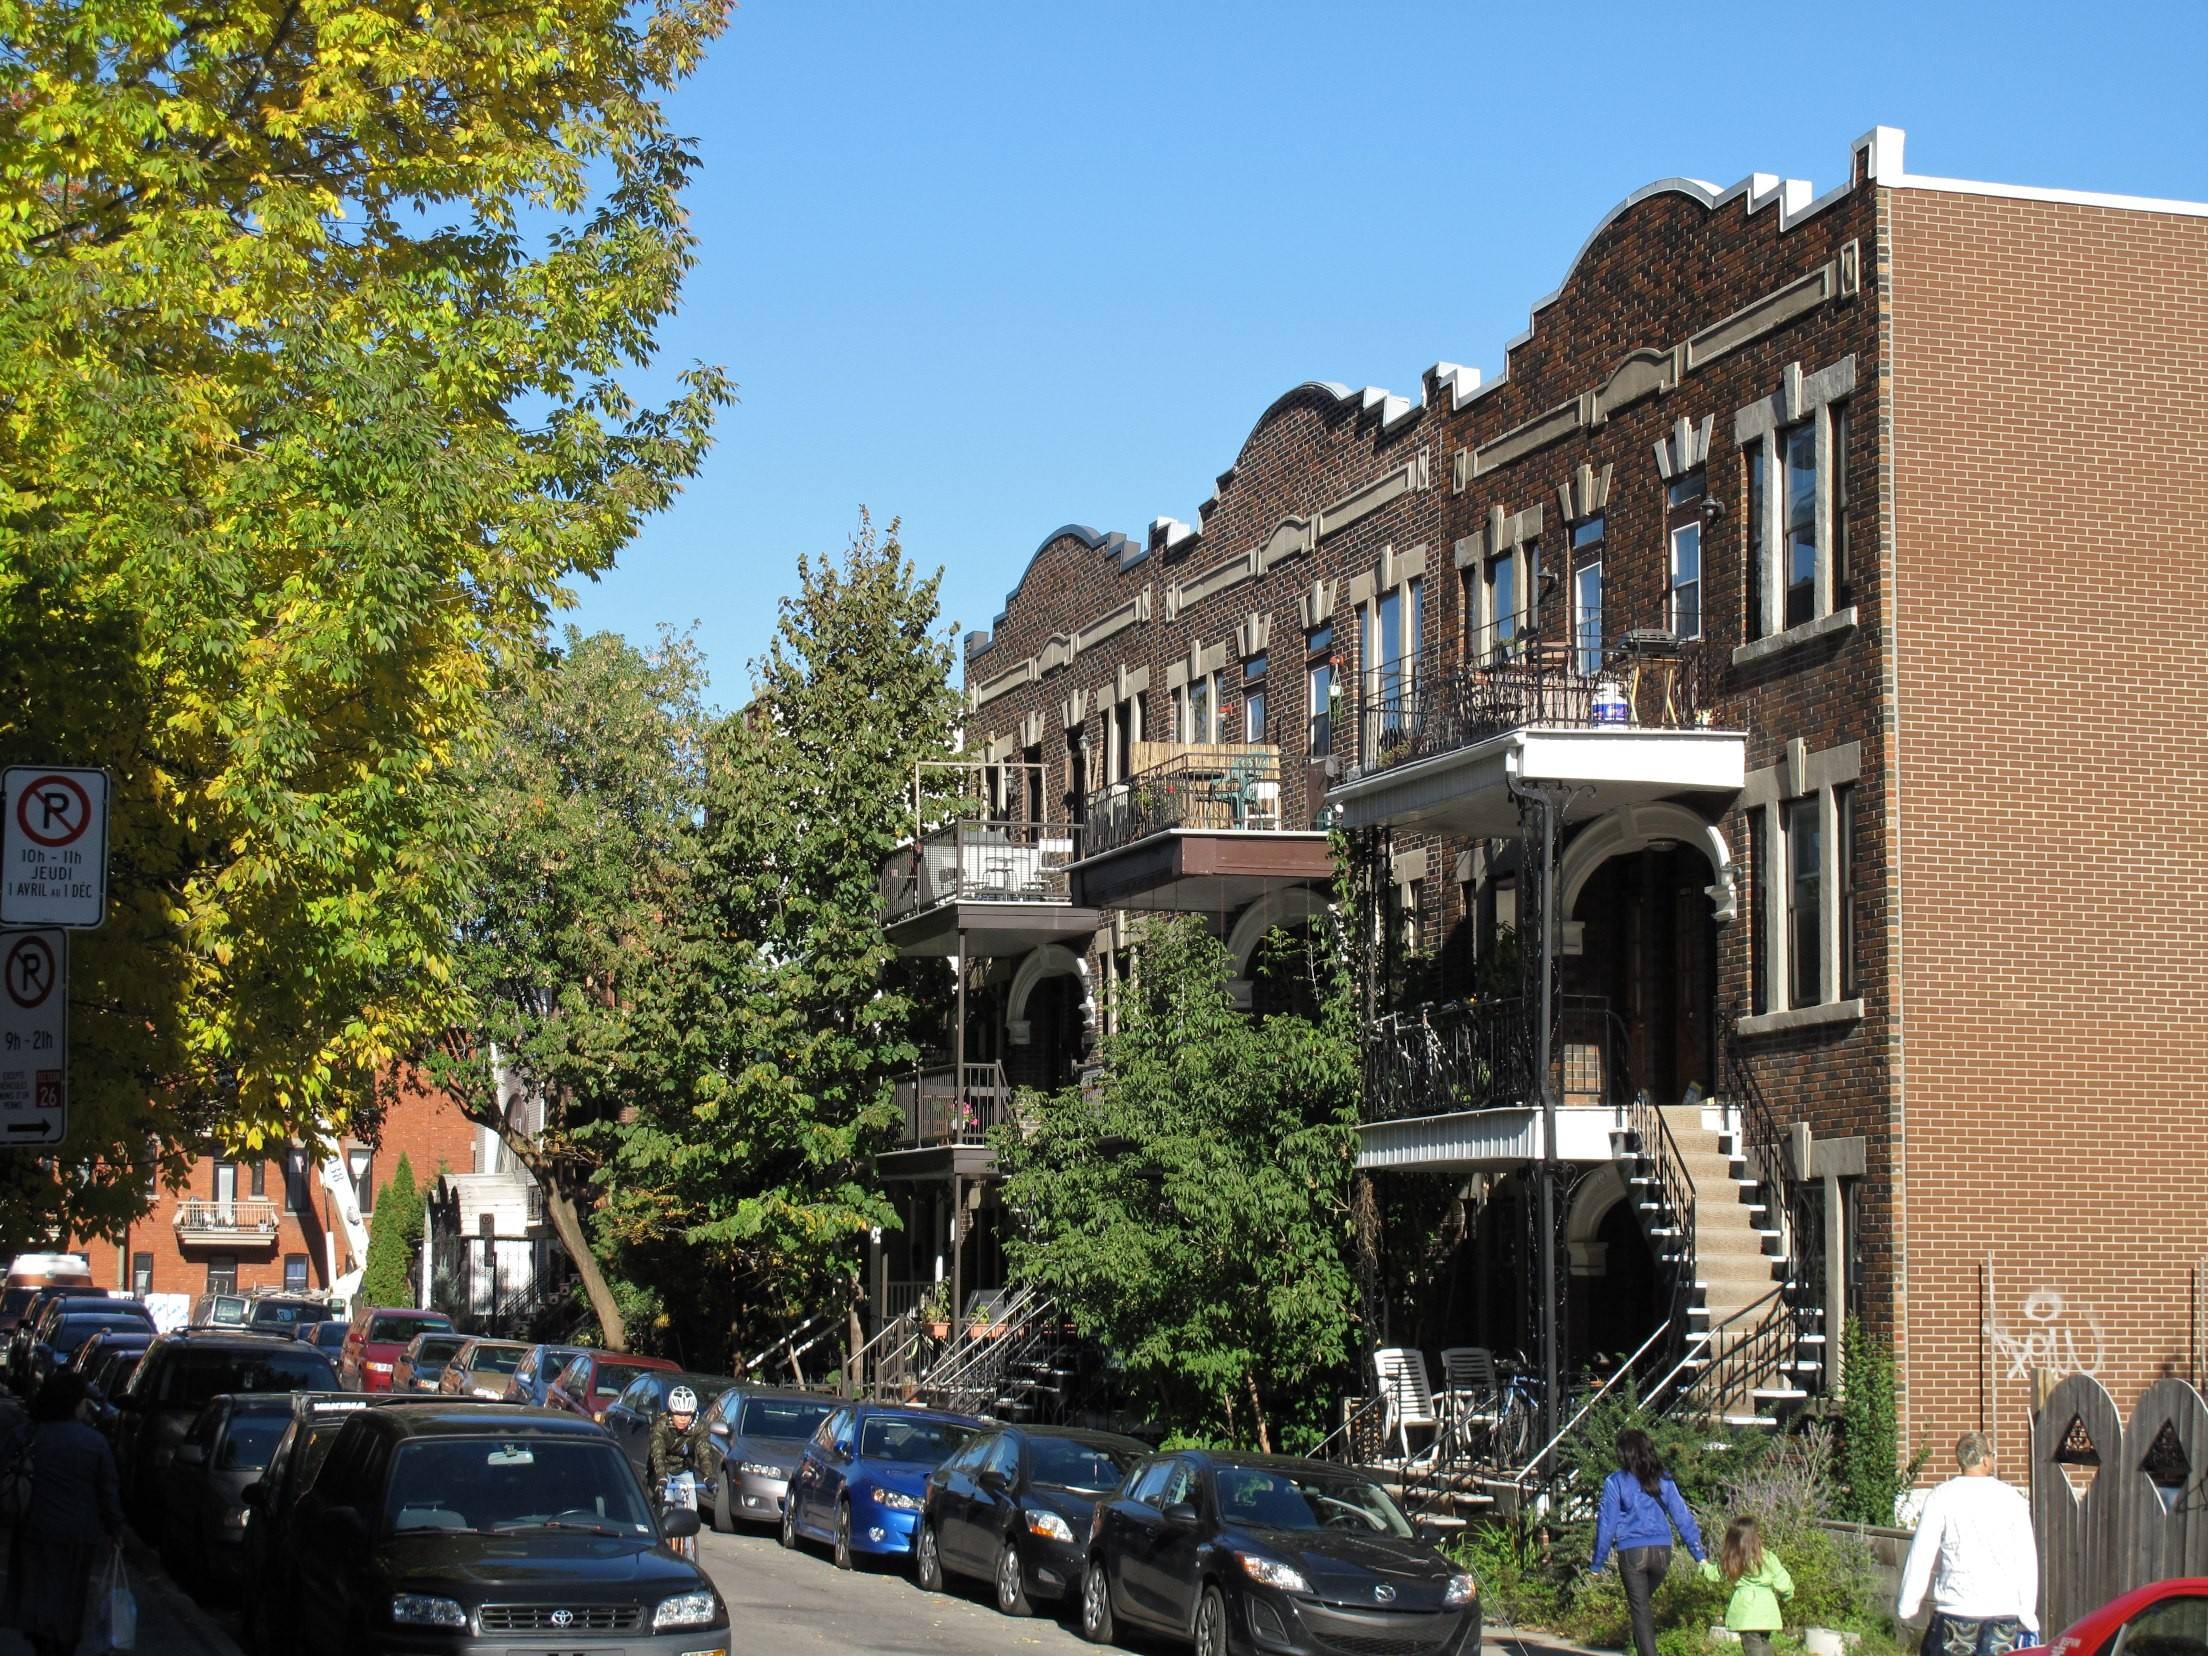
Montreal is two or three markets at once: a dense Island with a large condo stock, plexes owned by people who live in one unit, and suburbs across two bridges. A second hypothec behaves differently in each.
Montreal’s Q3 medians and the equity they imply
QPAREB’s October 2026 release recorded 3,252 residential sales in the Montreal metropolitan area, down 18% from October 2025 and about 13% below the ten-year average. Active listings reached 21,817, up almost 20%. Across the area, the median single-family price rose 2% on the year while condominium and plex medians were stable, and single-family homes sold in an average of 36 days, plexes in 46 and condominiums in 56.
The release says conditions still generally favour sellers, except for Island condominiums in central areas, which still show a surplus. The Q3 release put the metropolitan single-family median at $645,500 and the condo median at $435,000. On the Island alone, Centris reports Q3 medians of $812,000 for a single-family home, $477,000 for a condominium and $902,500 for a plex, with Island condominium sales down 15%.
Montreal’s 2021 population was 1,762,949.
A plex, a condo and one 80% ceiling in Montreal
The Quebec term for a second mortgage is second hypothec (deuxième hypothèque). The Financial Consumer Agency of Canada names 80% of the appraised value minus the mortgage balance as the limit, although a Montreal lender can use a different figure. In the plex example, a $500,000 first hypothec leaves $222,000 of room, and $102,000 remains after a $120,000 second. In the condo example, a $330,000 first hypothec leaves $51,600, and a $50,000 loan leaves $1,600.
A plex owner often has the most room and the most complexity, because rents count. A central condo owner has the least room and the least certainty. The calculator will show your own numbers.
Costs: the welcome tax and what it does not touch
The City’s property transfer duty, the welcome tax (taxe de bienvenue), is charged on purchases. For 2026 Montreal’s brackets are 0.5% up to $62,900, 1% to $315,000, 1.5% to $552,300, 2% to $1,104,700, 2.5% to $2,136,500, 3.5% to $3,113,000 and 4% above that. On an $812,000 purchase, which is the Island single-family median, that works out to $11,589 by our arithmetic. A second hypothec on a home you keep is not a transfer, and we found no Montreal duty on it.
What you do pay is the notary. A Quebec hypothec on a house is signed before a notary who prepares the deed and publishes it at the land register, as CMHC’s instructions to notaries for a second-ranking hypothec show. Ask the notary for a written quote, plus the lender’s fee and an appraisal.
The notice period if a Montreal owner defaults
Before a creditor can use a hypothecary right on a building, it must register a prior notice, and under article 2758 of the Civil Code the time given to surrender the property is 60 days from registration for an immovable. The notice must also name every default and remind the debtor of the right to remedy it, according to the Registre foncier. Speak to a notary or lawyer the day a notice arrives, and read our guide to private second mortgages for how the order of repayment works.
The rate and renewal picture
QPAREB noted the Bank of Canada’s policy rate increase of late October 2026 and said it could reinforce the shift toward more affordable areas. Its market analysis director added that plex inventory is up 28% and that higher financing costs may undermine plex profitability. If you own a plex, price a refinance with your first lender before adding a second. See second mortgages on rental property and renewal payment shock.
Island versus suburbs
A house on the Island is priced very differently from one a bridge away. The Q3 2026 Centris single-family medians were $812,000 on the Island, $645,000 on the South Shore, $630,000 in Laval and $597,500 on the North Shore. That makes the Island median $214,500 above the North Shore’s. The same 80% ceiling therefore means a much larger dollar amount of potential room on the Island, and a much larger first hypothec for many owners there.
Condos run the other way in one respect. The Island condo median was $477,000, flat on the year, while the South Shore’s was $407,500 (up 1%) and the North Shore’s $376,000 (flat). If you own a central condo, do not assume the metropolitan figures describe your building.
Compare your own street’s recent sales with the sector median, and use the lower of the two when you size a loan.
Finding a Montreal professional you can check
For who licenses mortgage professionals in Quebec and which questions to ask, the Quebec page is the place to read first. If you then want a professional’s view of your Montreal numbers, see where your options stand.
A Montreal Island duplex at the Q3 2026 plex median
The $902,500 value is the Centris Q3 2026 median price for a plex of two to five units on the Island of Montreal, used as a stand-in for an appraised value. The $500,000 first hypothec and the $120,000 second are made up. The 80% ceiling is the one the Financial Consumer Agency of Canada gives for a second mortgage; a Quebec lender may use another figure.
- Home value used
- $902,500
- 80% of the property value
- $722,000
- Room under the ceiling before any loan
- $222,000
- Combined loan-to-value with a $120,000 loan
- 68.7%
- Room left under the ceiling after the loan
- $102,000
$902,500 x 0.80
$722,000 minus $500,000
$620,000 / $902,500
A Montreal Island condo at the Q3 2026 condominium median
The $477,000 value is the Centris Q3 2026 median condominium price on the Island of Montreal, used as a stand-in for an appraised value. The $330,000 first hypothec and the $50,000 loan are made up.
- Home value used
- $477,000
- 80% of the property value
- $381,600
- Room under the ceiling before any loan
- $51,600
- Combined loan-to-value with a $50,000 loan
- 79.7%
- Room left under the ceiling after the loan
- $1,600
$477,000 x 0.80
$381,600 minus $330,000
$380,000 / $477,000
Questions people ask
When I take out a second hypothec, does Montreal's welcome tax apply?
The City's page describes duties on property transfers, calculated on the tax base of a sale. A second hypothec on a home you keep is not a transfer, and we found no Montreal duty line for it. Your notary will itemise the fees for your own deed.
Montreal condo or house: which is harder to borrow against?
It can be. QPAREB said central Island condominium areas still show a surplus in October 2026, and the Q3 Island condo median was flat at $477,000. A flat or falling value shrinks the room under a lender's ceiling, and building details matter too.
Default in Quebec: how long before a lender can act?
Before using a hypothecary right on a building, the creditor must register a prior notice, and the Registre foncier says the deadline is 60 days from registration for an immovable. A lawyer or notary should explain what that means for your file.
Are Montreal plex owners treated differently?
Lenders value plexes partly on rental income. The Island's Q3 2026 plex median was $902,500, and QPAREB noted inventory up 28% and median price growth moderating since August. Rents and vacancies on your own units will drive the appraisal.
Bank of Canada rate increase: will Montreal lenders change their offers?
QPAREB pointed to the Bank of Canada's policy rate increase of late October 2026 as a possible drag on buyers in the coming months. Second hypothec pricing is set by each lender, and we cannot state a rate, so ask each lender for its terms in writing.
Sources
- QPAREB: Centris Residential Sales Statistics, October 2026, Montreal CMA (press release, 6 November 2026), 2026-11-06
- APCIQ and QPAREB: Third quarter 2026 residential market release, 2026-10-14
- Centris: Real estate statistics, Montreal (Island), 3rd quarter 2026, 2026-Q3
- Centris: Real estate statistics, Montreal (South Shore), 3rd quarter 2026, 2026-Q3
- Centris: Real estate statistics, Montreal (North Shore), 3rd quarter 2026, 2026-Q3
- Centris: Real estate statistics, Laval, 3rd quarter 2026, 2026-Q3
- Ville de Montreal: How property transfer duties are calculated, 2026
- Statistics Canada: Table 98-10-0002-01, Population and dwelling counts, 2021 Census
- Registre foncier du Quebec: Prior notice of exercise of a hypothecary right (art. 2757 and 2758 C.C.Q.), 2024-11
- CMHC: Instructions to Notary (Quebec), second-ranking hypothec
- Financial Consumer Agency of Canada: Borrowing against your home equity