
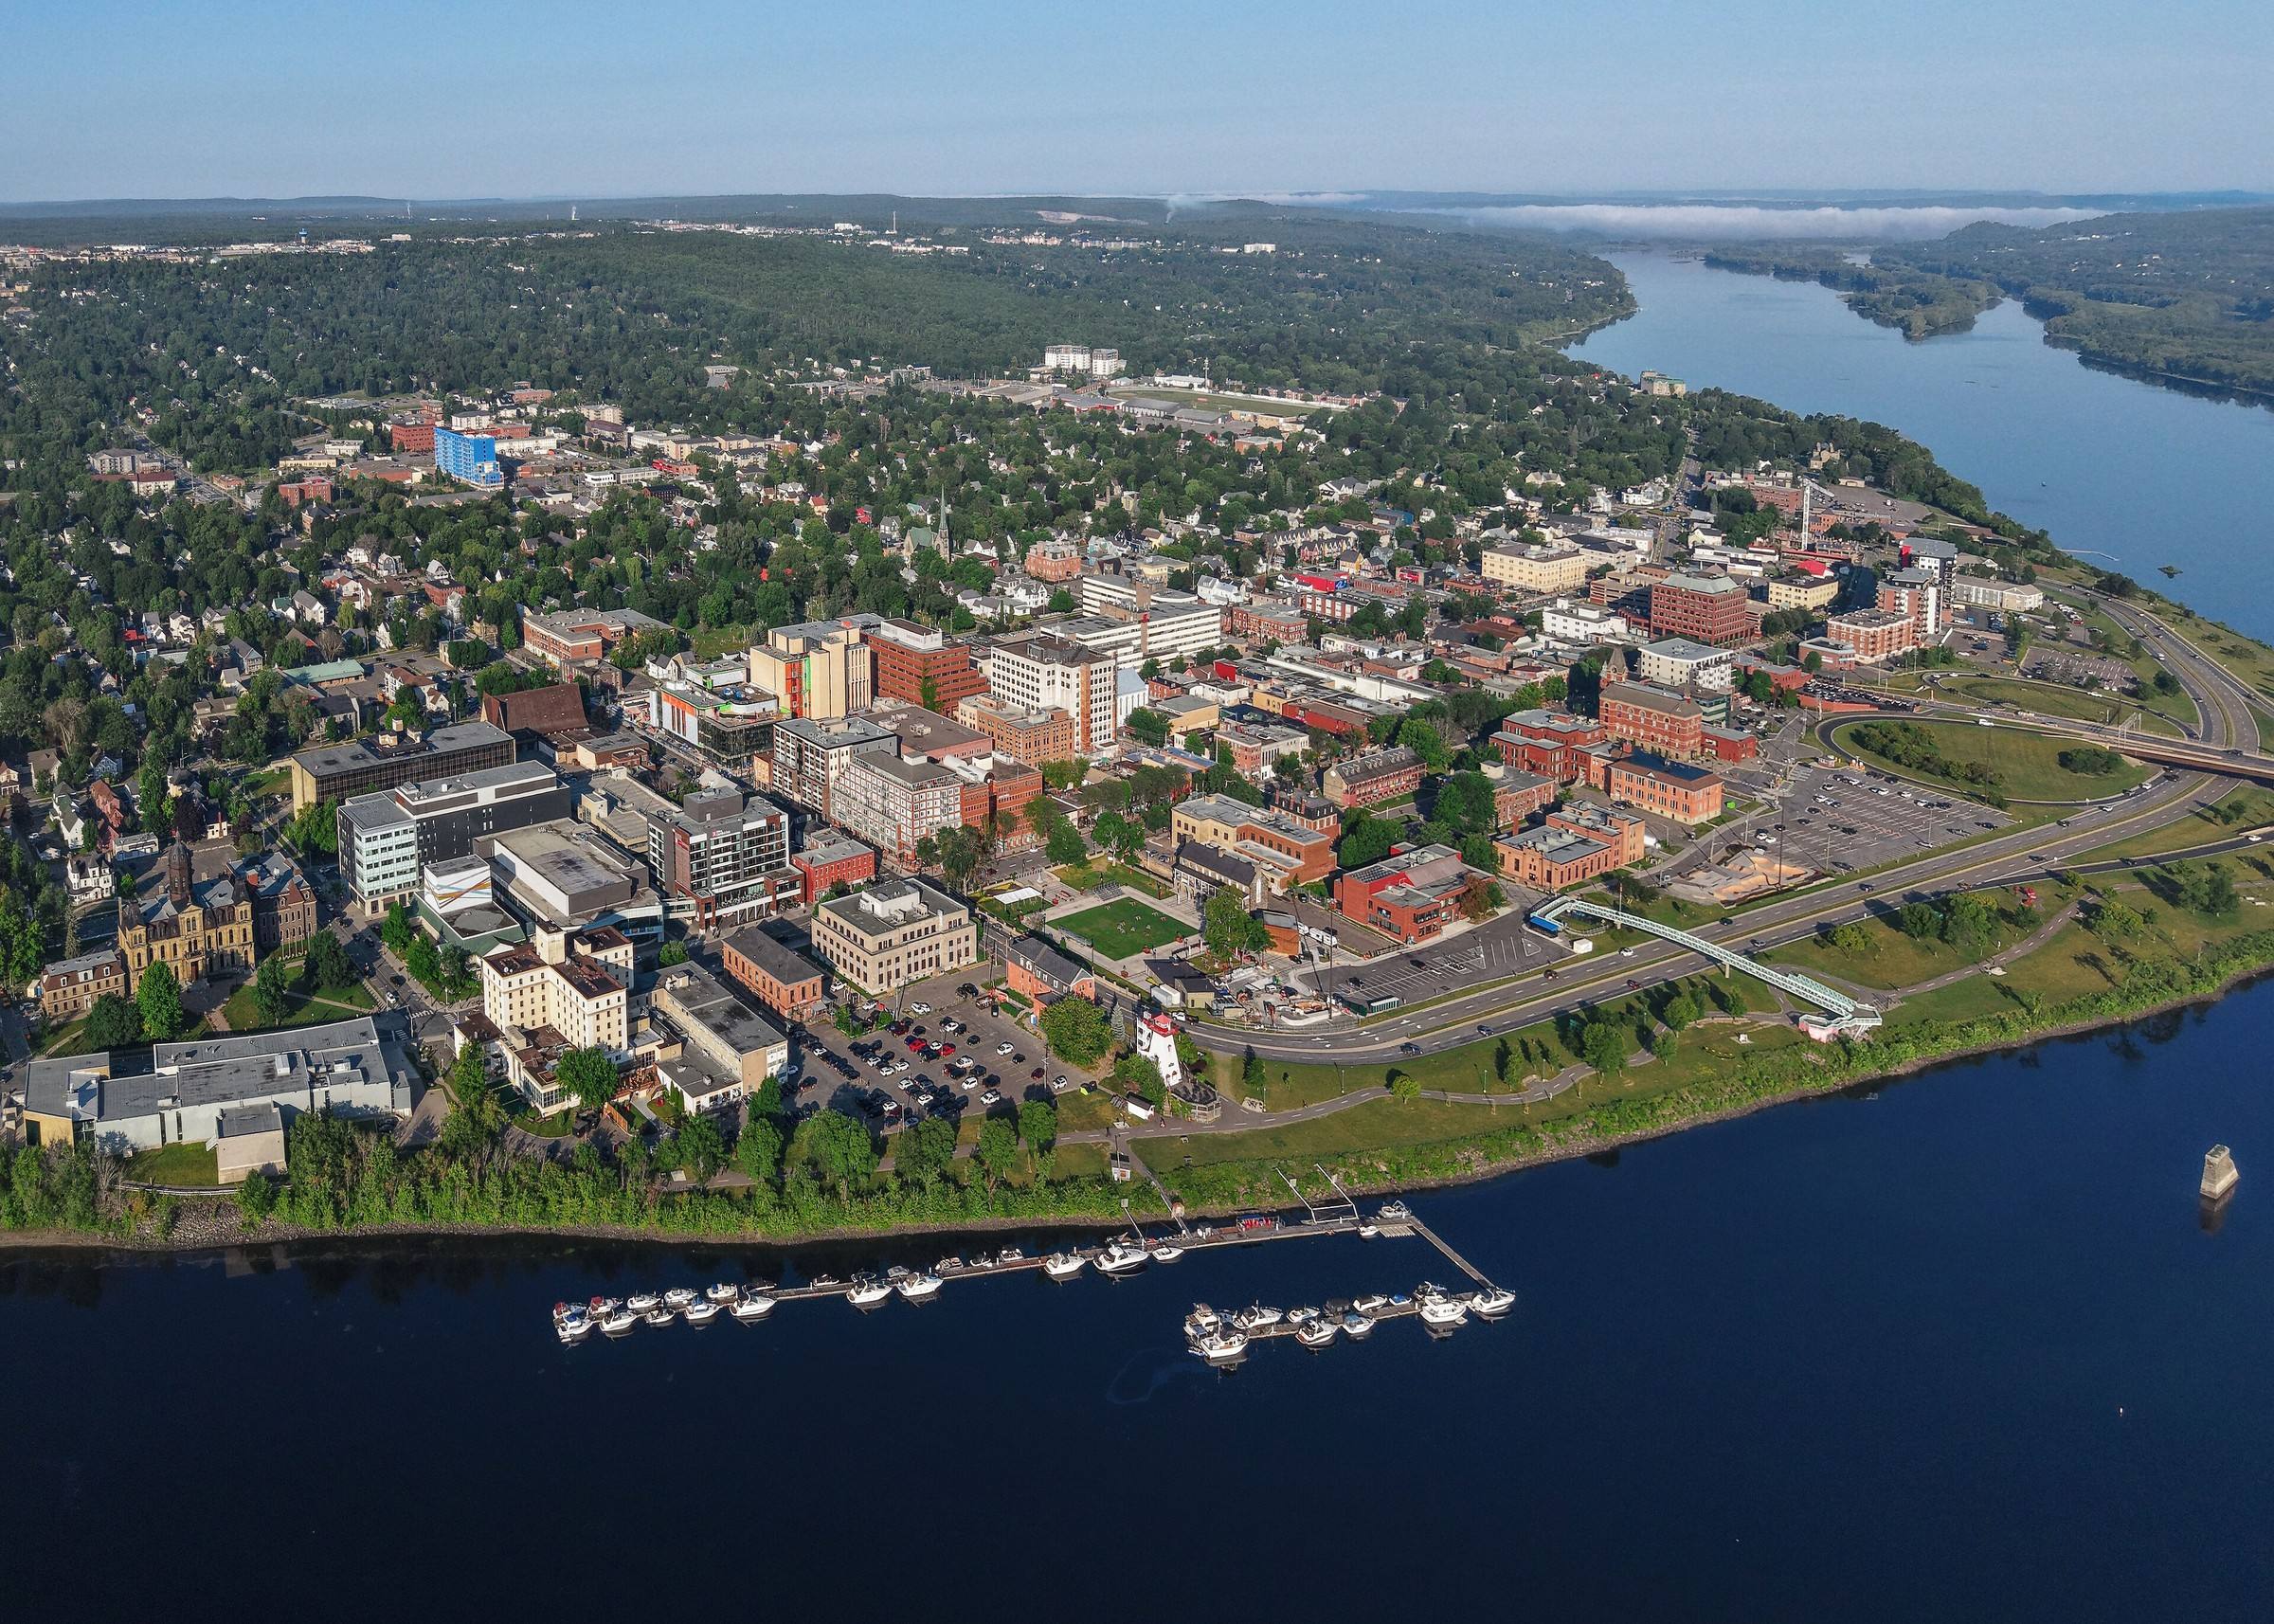

- Fredericton sales change from a year earlier
- Down 9.1%As of September 2026.Source
- Composite MLS HPI benchmark, New Brunswick (no Fredericton figure published)
- $341,700 (up 2.7%)As of September 2026.Source
- Active listings, New Brunswick
- 4,049, up 5.8%As of September 2026.Source
- Population of the City of Fredericton
- 63,116As of 2021 Census.Source
On this page
Owners with a modest first mortgage have the most room under a lender’s ceiling, and they are also the ones who should look hardest at the monthly cost of a loan. That is the thread through this page.
Fredericton: sales down, benchmark up
New Brunswick’s board published no Fredericton price in its September 2026 report, so we use provincial figures: a composite benchmark of $341,700, up 2.7% from a year earlier, a single-family benchmark of $342,800 and an apartment benchmark of $293,100. Fredericton sales were down 9.1%. Province-wide, active listings were 4,049, up 5.8%, and months of inventory were 5.6.
Fredericton had 63,116 residents in the 2021 count. Without a local price series, your own appraisal does the work, and it can land above or below the provincial number.
Sizing a $75,000 loan against the provincial benchmark
Under the Financial Consumer Agency of Canada’s guidance, the room for a second mortgage is 80% of the appraised value minus what is owed on the first. With a $150,000 first mortgage on a $341,700 home, equity is $191,700 and room is $123,360, enough for a $75,000 loan. The calculator lets you see where your balance puts you.
Room is only half the question. The second example shows what the same loan costs each month at three made-up rates. At 9% interest only it is $562.50, and at 13% it is $812.50.
Transfer tax in New Brunswick and a loan on a home you keep
New Brunswick’s real property transfer tax is 1% of the greater of the price or the assessed value, which is $3,417 on a purchase at $341,700. The Act exempts a deed used only to secure a debt or loan, which is the position of a mortgage on a home you keep.
Expect to pay lender and broker fees, an appraisal, legal costs and registration instead. The New Brunswick page goes through each cost.
Few sales means careful appraisals
A 9.1% drop in sales is not a collapse, but it means fewer recent examples to compare yours against. Ask what a lender uses as comparables, and gather a recent property tax bill and mortgage statement. If your home has a legal suite, an acreage or an unusual layout, say so early, since those details can change an appraisal.
The loans Fredericton owners tend to ask about
Owners who work for themselves read the self-employed page, because banks can discount that income. Owners planning improvements read the renovation page, where the question is whether the work adds value. Older owners weighing cash against a sale of the home compare reverse mortgages, which are repaid very differently.
Nearby markets are on the Saint John, Moncton and Halifax pages.
The size of the market behind the numbers
New Brunswick’s September 2026 report gives the scale. There were 724 sales across the province, worth $250.9 million, down 12.1% in dollar volume, which works out to roughly $346,500 per sale on average. Year to date the province had 6,989 sales, down 6%. New listings were 1,291, nearly flat, and months of inventory were 5.6 against 4.6 a year earlier.
Fredericton’s 9.1% fall in sales sits between Saint John’s gain and Greater Moncton’s drop. With a population of 63,116, the city has a limited pool of buyers at any time, which makes each recent sale count for more in an appraiser’s comparison. If your home is unusual, ask a lender early what sort of comparable it needs. A conventional house on a regular lot is easy to compare. A property with acreage, a suite or a heritage feature is not.
Ask to see the full offer on paper, including every fee in dollars and the length of the term. A short-term loan has to be repaid or replaced when it matures, and the cost of replacing it depends on the market that day. If the payment from your made-up budget only works at the cheapest rate you were shown, treat that as a warning, not a plan.
Who to speak to in Fredericton
A licensed mortgage professional in New Brunswick can compare lenders for a Fredericton loan. Confirm the licence before any documents change hands. To have someone look over your numbers, see how your options compare.
A Fredericton-area home at the provincial benchmark, with a $75,000 loan
The $341,700 value is the New Brunswick composite MLS HPI benchmark for September 2026, used as a stand-in because no Fredericton benchmark was published. The $150,000 first mortgage and $75,000 new loan are made up. The 80% ceiling is the one the Financial Consumer Agency of Canada gives for a second mortgage.
- Home value used
- $341,700
- Equity before the new loan
- $191,700
- 80% of the home value
- $273,360
- Combined loan-to-value with a $75,000 loan
- 65.8%
- Room left after the new loan
- $48,360
- Room under an 80% ceiling before the loan
- $123,360
$341,700 minus $150,000
$341,700 x 0.80
$225,000 divided by $341,700
$273,360 minus $225,000
Monthly interest on a $75,000 second mortgage at three made-up rates
Made-up rates of 9%, 11% and 13%, interest only, before lender fees, legal costs or any payment on the first mortgage. These are not typical or current rates.
- Yearly interest at 9%
- $6,750
- Monthly interest at 9%
- $562.50
- Monthly interest at 11%
- $687.50
- Monthly interest at 13%
- $812.50
- Monthly gap between 9% and 13%
- $250.00
$75,000 x 0.09
$6,750 divided by 12
$75,000 x 0.11 divided by 12
$75,000 x 0.13 divided by 12
Questions people ask
Fredericton had fewer sales. Does that affect a loan against my home?
It can. Sales were down 9.1% in September 2026, and fewer recent sales means fewer comparables for an appraiser. Ask the lender how recent a comparable must be and whether it must be on or near your street.
Monthly cost of interest-only on a $75,000 second mortgage?
At the made-up rates in our example, 9% costs $562.50 a month, 11% costs $687.50 and 13% costs $812.50, before any fees. A lender will set the real rate, so use the figures only to test your budget.
Renovation loan or reverse mortgage: what separates them?
A renovation second mortgage is repaid on a schedule you agree. A reverse mortgage is usually for older owners and is repaid when you sell or move. Read both pages, since the costs and the effect on your equity differ.
If I run my own business, can I get a second mortgage on a Fredericton home?
Possibly. Lenders may count your income differently if you are self-employed and often want tax returns and notices of assessment. The self-employed page explains what lenders tend to ask and what it can cost.
Does New Brunswick's transfer tax apply to a refinance in Fredericton?
The 1% property transfer tax applies when a deed is registered for a transfer of ownership, and the Act exempts a deed used only to secure a debt. A loan secured on a home you keep is on the exempt side.