

- Residential benchmark price, Regina
- $343,900As of September 2026.Source
- Residential benchmark price, Regina
- $348,900As of August 2026.Source
- Residential sales, Regina
- 327 (down 13% from a year earlier)As of September 2026.Source
- Months of supply entering October, Regina
- 2.54, up from 1.72 in early SeptemberAs of September 2026.Source
- Population of the Regina census metropolitan area
- 249,217As of 2021 Census.Source
On this page
Regina’s benchmark sits about $95,700 below Saskatoon’s, so the same first mortgage takes a bigger bite out of your room here. That makes the arithmetic of borrowing sensitive to your balance.
Regina’s September benchmark and your equity
The Saskatchewan REALTORS Association, through CREA, put Regina’s residential benchmark at $343,900 in September 2026, up 3% from a year earlier and down from $348,900 in August. The month had 327 residential sales, 13% fewer than a year before and nearly 15% above the 10-year average. Months of supply entering October were 2.54, up from 1.72 early in September. Nearly 500 new listings arrived, the third monthly gain in a row.
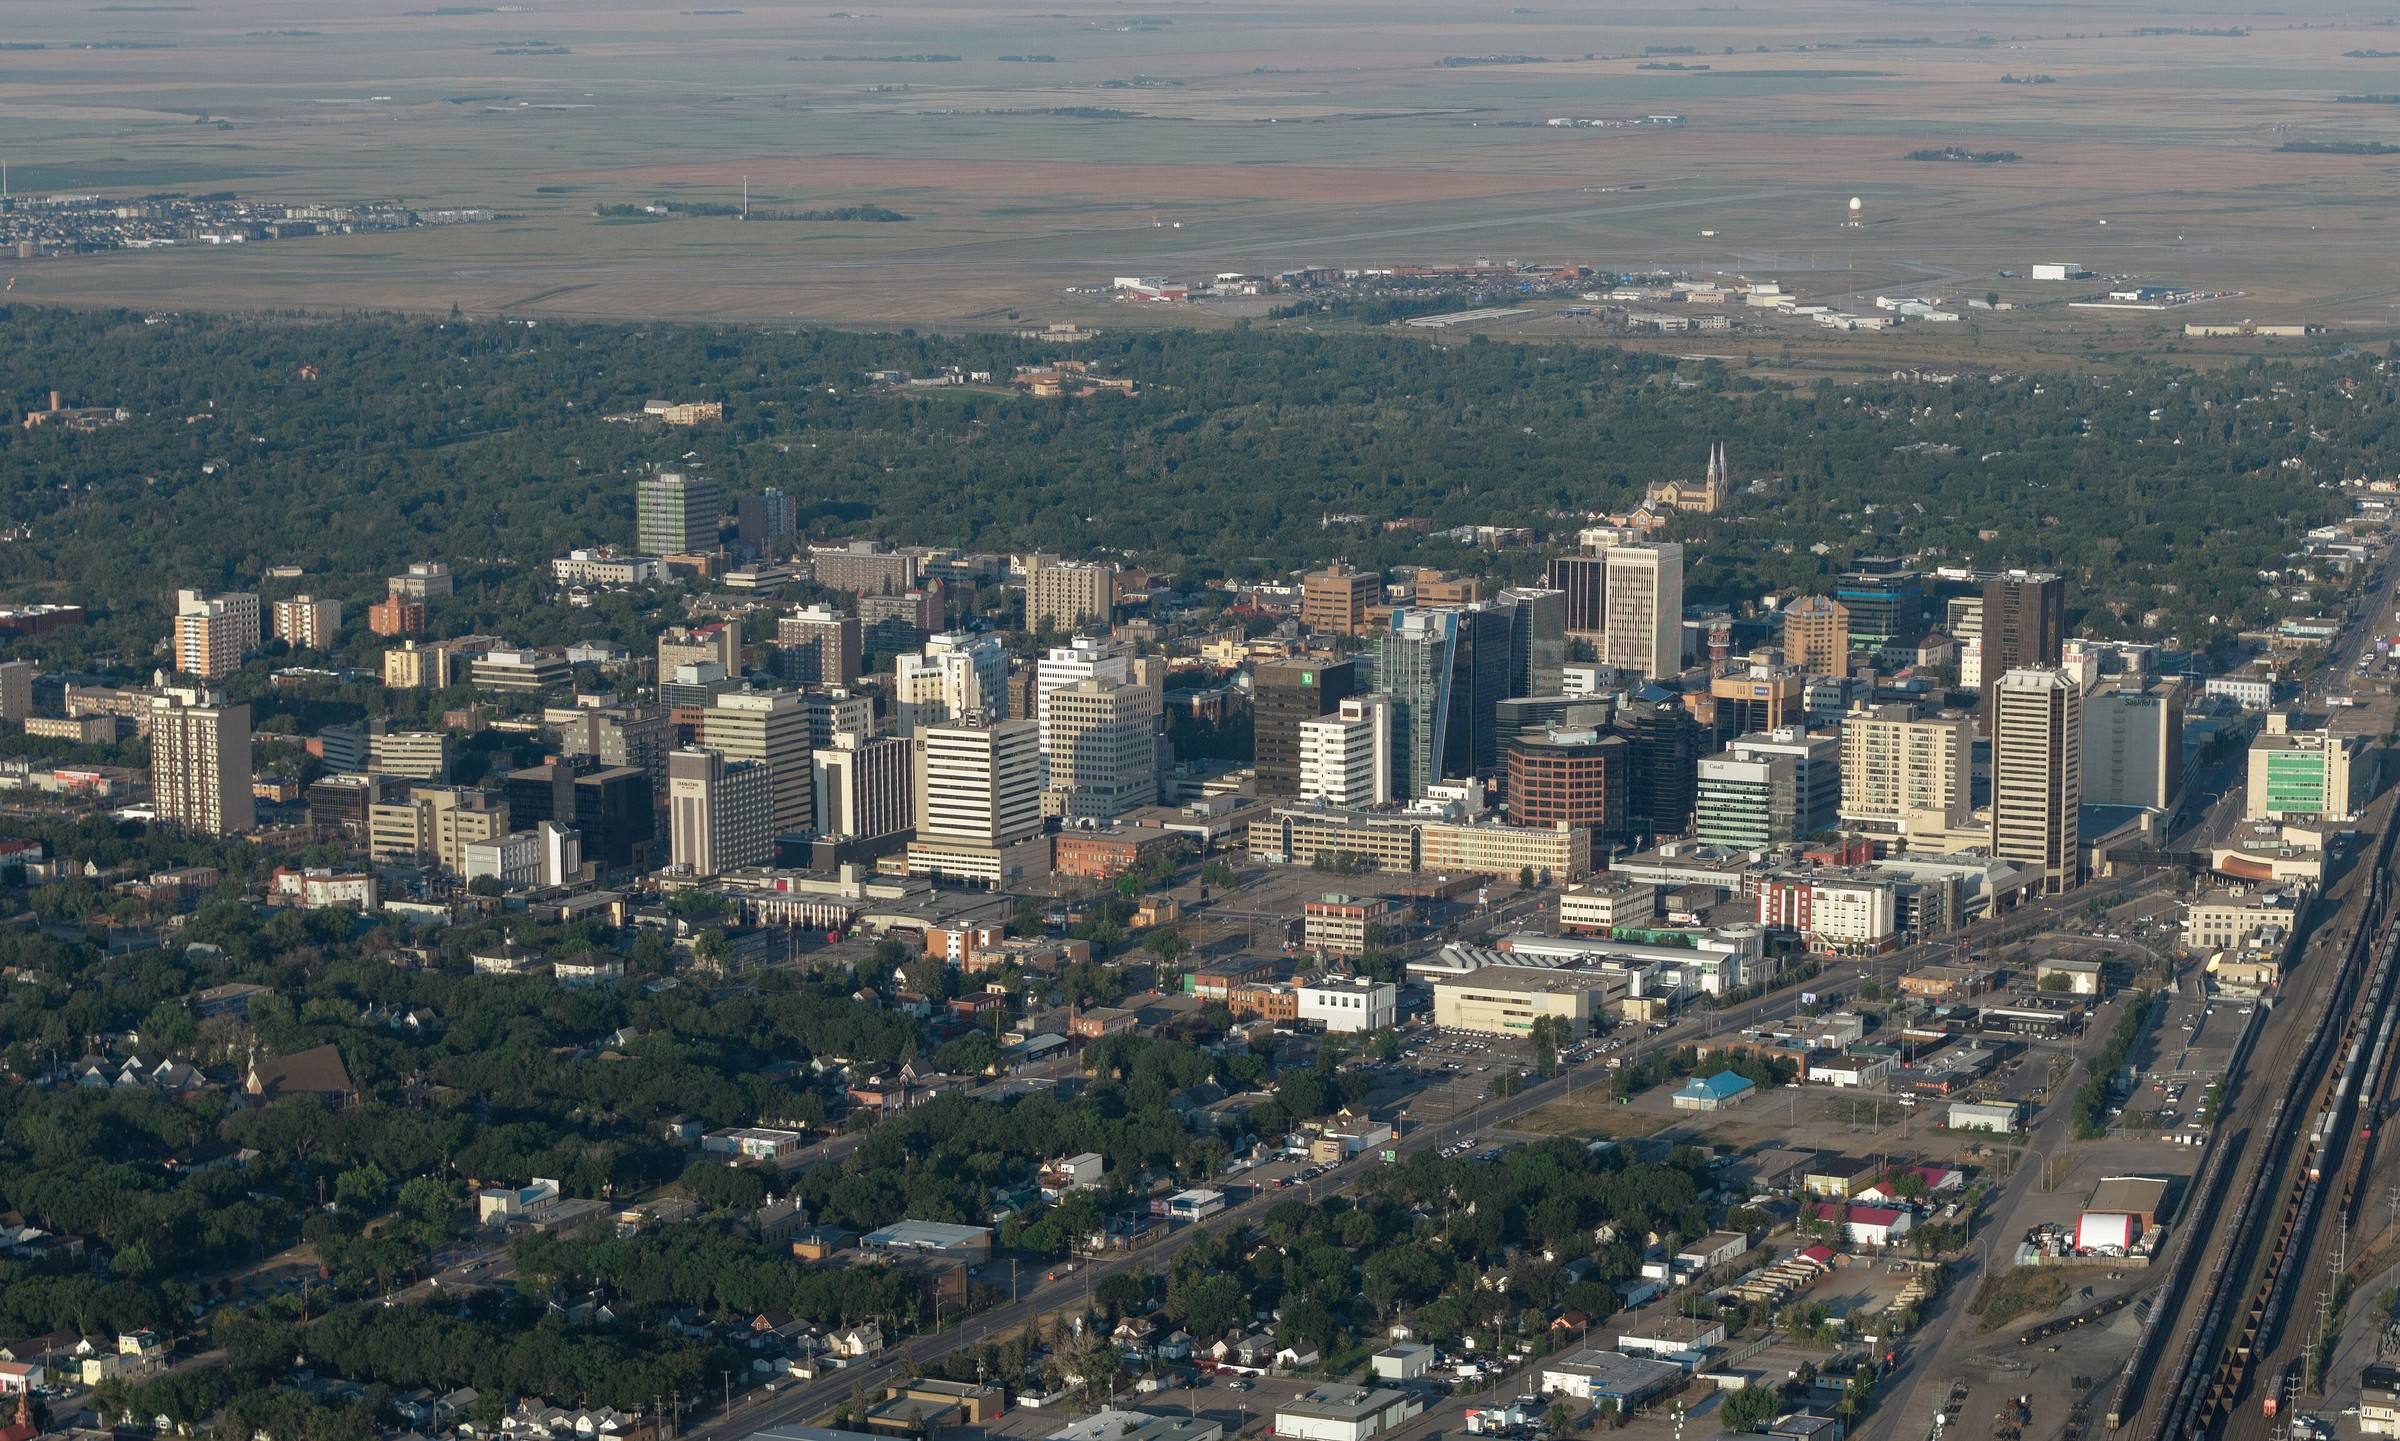
In 2021 the Regina census metropolitan area was home to 249,217 people. The association did not publish an average sale price for Regina in this release, so the benchmark is our guide.
What a $210,000 balance leaves in Regina
A lender thinks in terms of total debt against value. The Financial Consumer Agency of Canada puts the limit at 80% of appraised value, so the first mortgage and the new loan together should fit under that line. In the first example a $210,000 balance leaves $65,120 of room. In the second, a $255,000 balance cannot carry a $50,000 loan at all.
Turn the rule around and it tells you what you need: divide the total debt by 0.80. A $305,000 total needs a home worth $381,250. Test your own totals in the calculator.
Saskatchewan’s registry fees
Saskatchewan has no traditional land transfer tax. Fees are charged by Information Services Corporation instead. The guide we read, for fees effective April 15, 2026, lists $200 to register a mortgage under $250,000 and $275 from $250,000 to $500,000. A title transfer, which only happens when ownership changes, is about 0.4% of value.
On a $50,000 second mortgage the registry fee is $200. The larger costs are the lender fee, broker fee, appraisal and legal work, set out on the Saskatchewan page.
A market that is easing
More supply helps buyers, and it can make lenders watchful. When months of supply move from 1.72 to 2.54 in a few weeks, an appraiser may look harder at recent comparable sales on your street. That does not mean your home is worth less. It means the evidence for its value should be recent and close by.
Prepare your mortgage statement, property tax bill and a plain list of debts, and ask any lender how old a comparable sale can be.
Choices to read before you apply
If a bank has already declined you, the B lender page explains what the alternative lender tier looks like and what it costs. If the first mortgage itself has to come from a private lender, see private first mortgages. If a relative’s share of an inherited house is the issue, read the estate buyout page.
Regina’s neighbour is covered on the Saskatoon page, and the nearest Manitoba cities are Brandon and Winnipeg.
How a one-month dip works through the ceiling
Regina’s benchmark moved from $348,900 in August to $343,900 in September 2026, a fall of $5,000 or about 1.4%. On a home valued at the benchmark, an 80% ceiling fell by $4,000 over that month, from $279,120 to $275,120. If your first mortgage was $250,000, your room went from $29,120 to $25,120 without you doing anything.
The association’s other September numbers show why the benchmark softened: 832 units were available at month end, nearly 200 were conditionally sold, and months of supply entering October stood at 2.54 against Saskatoon’s 2.13. A supply difference between the two cities is a reminder that Saskatchewan has no single housing market, a point the association’s own chief executive has made. Lenders know it too, so ask how they value a home in your neighbourhood, not in the province.
Insist on a written offer with the loan amount, the fees in dollars and the term. Ask whether the amount depends on an appraisal still to come, and what happens to the fees if the appraisal falls short. Some fees are paid whatever the outcome, so find that out first.
Checking a Regina professional’s licence
A licensed mortgage professional can compare lenders and explain costs. Ask for their Saskatchewan licence and check it with the regulator, the Financial and Consumer Affairs Authority. To have someone review your Regina figures, see your options.
A Regina home at the September 2026 benchmark, with a $35,000 loan
The $343,900 value is the September 2026 Regina residential benchmark price, used as a stand-in for an appraised value. The $210,000 first mortgage and $35,000 new loan are made up. The 80% ceiling is the one the Financial Consumer Agency of Canada gives for a second mortgage.
- Home value used
- $343,900
- Equity before the new loan
- $133,900
- 80% of the home value
- $275,120
- Combined loan-to-value with a $35,000 loan
- 71.2%
- Room left after the new loan
- $30,120
- Room under an 80% ceiling before the loan
- $65,120
$343,900 minus $210,000
$343,900 x 0.80
$245,000 divided by $343,900
$275,120 minus $245,000
What value does a $50,000 Regina loan need behind it?
The $343,900 value is the September 2026 Regina residential benchmark. The $255,000 first mortgage and $50,000 loan are made up. The 80% ceiling is the one the Financial Consumer Agency of Canada gives.
- Total owed with the new loan
- $305,000
- Value needed to stay at 80%
- $381,250
- Benchmark value used
- $343,900
- 80% of the benchmark value
- $275,120
- Amount the loan overshoots the ceiling
- $29,880
$255,000 plus $50,000
$305,000 divided by 0.80
$343,900 x 0.80
Questions people ask
What home value does a $50,000 loan in Regina call for?
Divide the total you will owe by 0.80. With a $255,000 first mortgage and a $50,000 loan, the home would need to be worth at least $381,250 to stay within an 80% ceiling. The September 2026 Regina benchmark was $343,900.
Is Regina's market starting to loosen?
The Saskatchewan REALTORS Association reported months of supply rising to 2.54 from 1.72 in early September 2026, with nearly 500 new listings, the third straight month of year-over-year gains. Sales were 327, down 13% but nearly 15% above the 10-year average.
Which mortgage registration fee applies in Regina?
Saskatchewan's land registry fee for a mortgage under $250,000 is $200 and from $250,000 to $500,000 is $275, according to a law firm's guide to fees effective April 15, 2026. Check the current fee table with your lawyer.
Will Regina's benchmark price tell me what my house will appraise at?
No. A benchmark describes a typical home, and an appraiser values yours: its size, condition, street and recent nearby sales. Treat the number as a starting guide only.
Estate buyout in Regina: can a second mortgage buy out a relative's share?
Some lenders consider it, and the details depend on who holds title and the loan amount. Read the estate buyout page first, then ask a lawyer how the buyout is documented before any money moves.
Sources
- Saskatchewan REALTORS Association via CREA: September 2026 summary, 2026-09
- Statistics Canada: Population and dwelling counts, 2021 Census (table 98-10-0005-01)
- SHD Law: Saskatchewan land title closing guide, fees effective April 15, 2026, 2026-04
- Information Services Corporation: Land title fees table
- Financial Consumer Agency of Canada: Borrowing against your home equity