
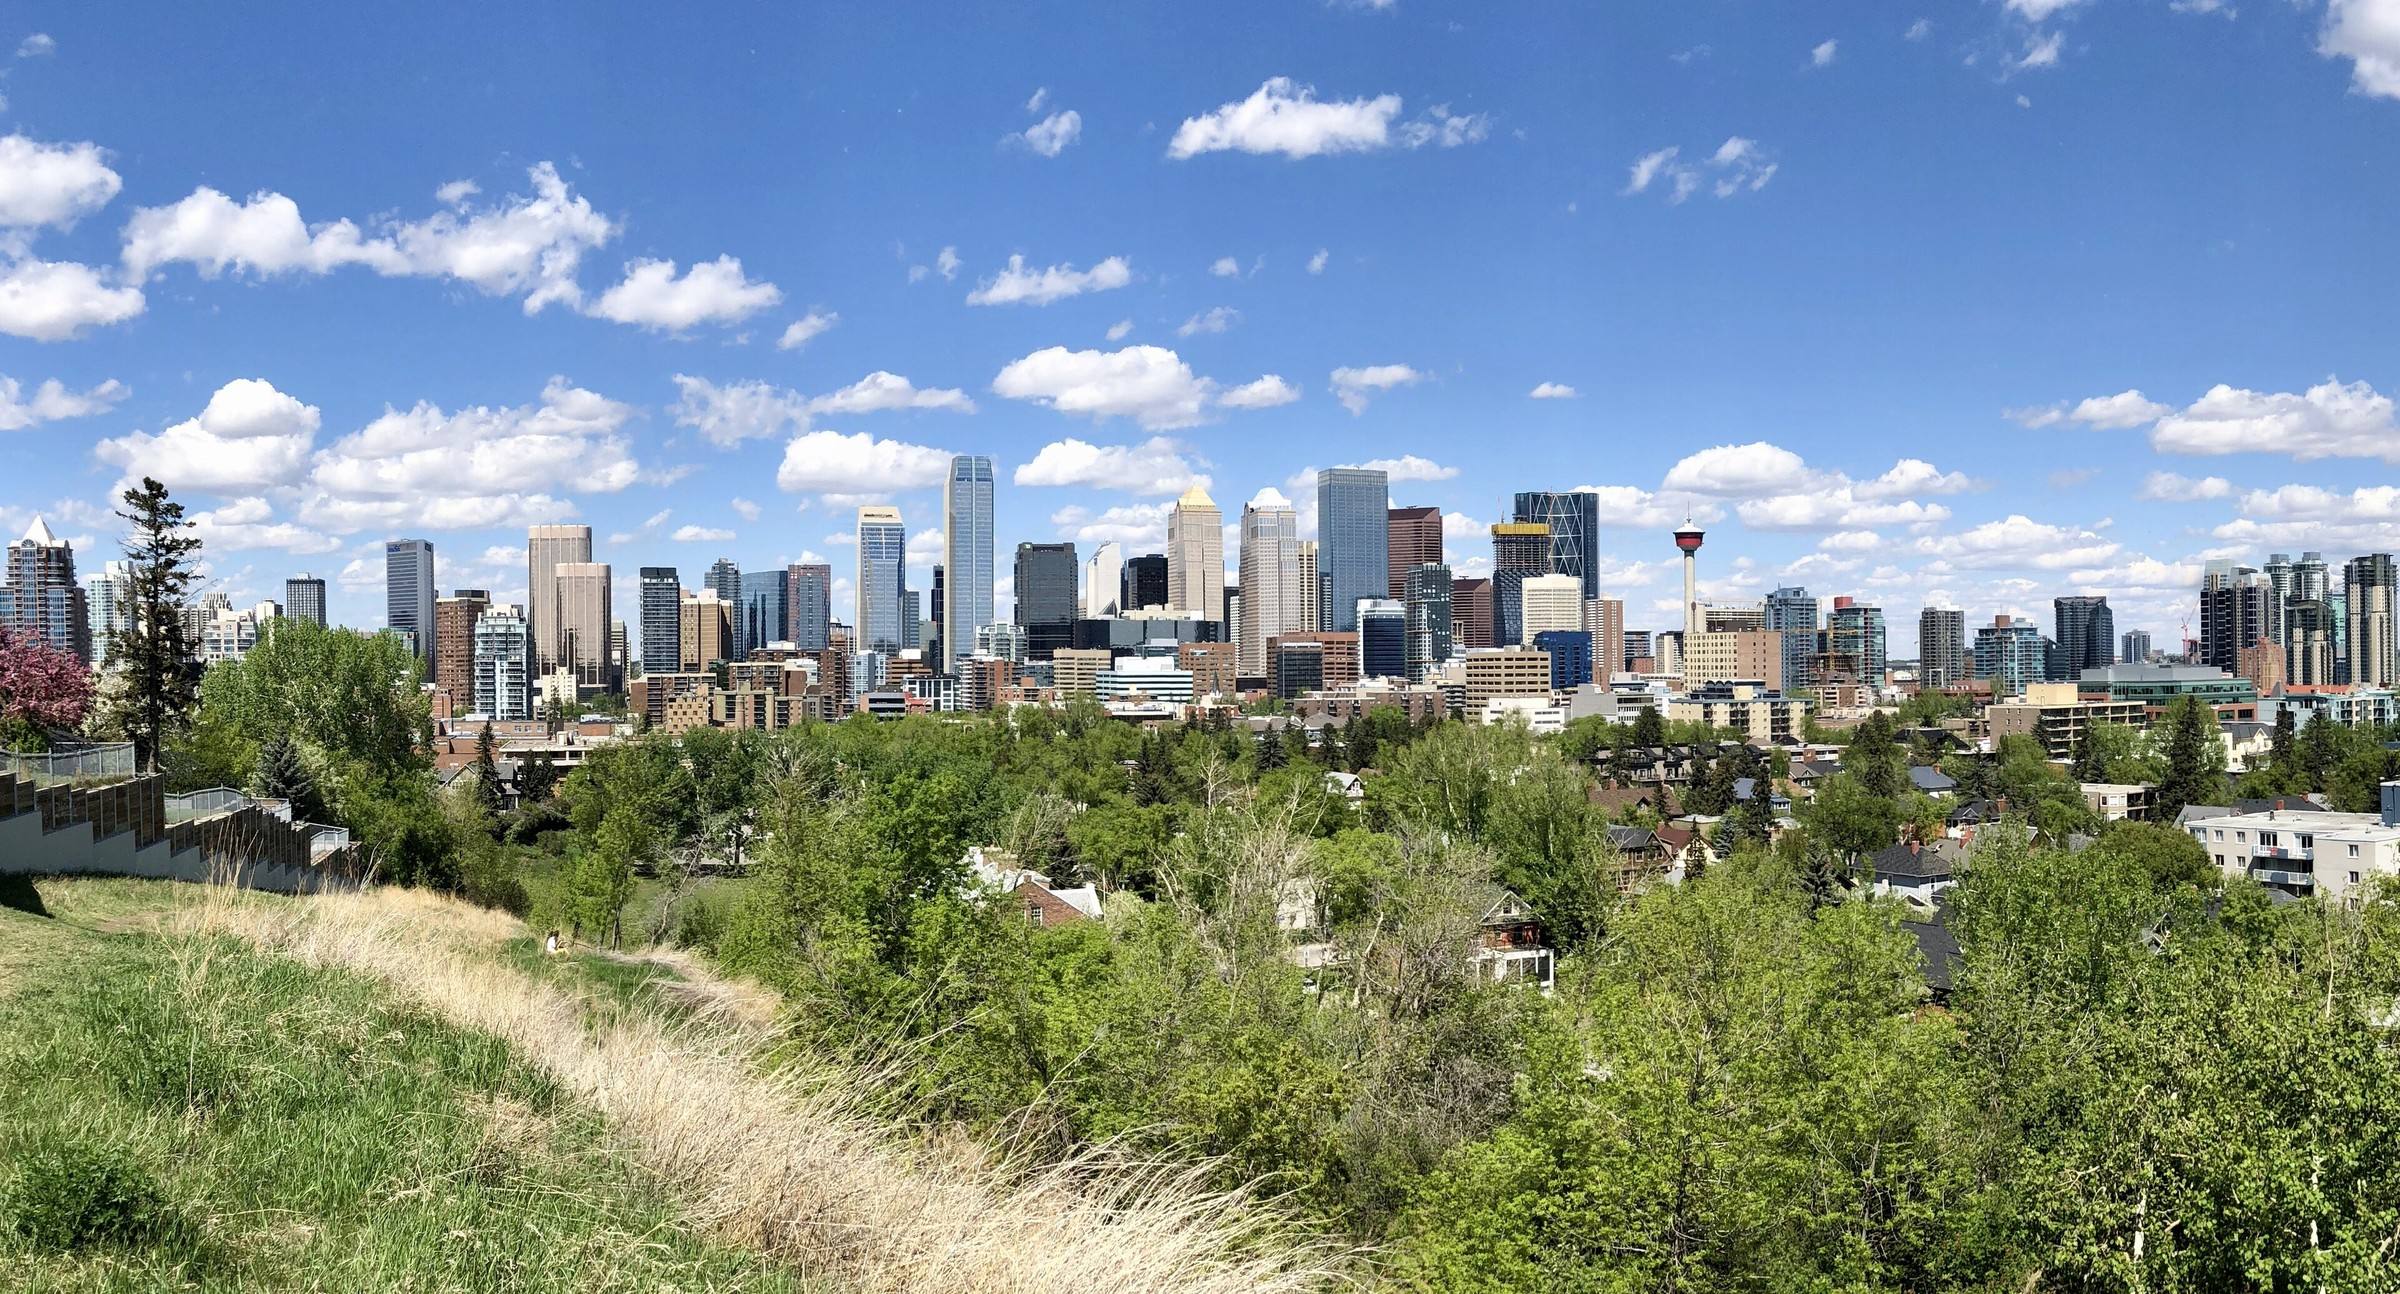

- Residential benchmark price, City of Calgary
- $564,200As of October 2026.Source
- Detached benchmark price, City of Calgary
- $735,100As of October 2026.Source
- Apartment benchmark price, City of Calgary
- $288,800As of October 2026.Source
- Population of the City of Calgary
- 1,306,784As of 2021 Census.Source
On this page
Calgary does not have one housing market. It has eight, one per district in CREB’s tables, and the gap between them is wider than most owners expect.
CREB’s October package, read for equity
CREB’s October 2026 package recorded 1,592 sales in the City of Calgary, 3.88 months of supply and a total residential benchmark of $564,200, with the average sale price at $640,769 and the median at $562,500. The 2021 Census put Calgary’s population at 1,306,784.
The benchmark hides the spread. Detached homes benchmarked at $735,100 in October, and by district that ranged from $463,800 in the East and $548,000 in the North East to $988,400 in the West and $992,500 in the City Centre. Apartments benchmarked at $288,800, down about 7.9% from a year earlier. If you own an apartment, your equity may be moving the wrong way even while your payments stay the same.
Room to borrow depends on your district
Equity is the value minus what you owe. A lender works from a ceiling instead, and the Financial Consumer Agency of Canada puts it at 80% of the appraised value, less your mortgage balance. The two examples above use real CREB district figures. In the North East, a $400,000 first mortgage leaves $38,400 of room, so a $50,000 loan overshoots. In the West, a $520,000 first mortgage leaves $270,720.
That is why a Calgary loan amount should never be quoted from the city-wide number. Before you talk to anyone, work out a range with the calculator, then expect an appraisal to move it.
Costs in Calgary: no land transfer tax, but not free
Alberta has no land transfer tax in the way Ontario does. What you meet instead is the Land Titles charge when a mortgage is registered. The Government of Alberta says that for submissions received on or after October 20, 2024 the registration levy is $5 for every $5,000 on both transfers and mortgages. On a $100,000 second mortgage that levy alone is $100, and a flat registration fee is added on top. We could not confirm the flat fee from the government page, so your lawyer’s statement is the figure to rely on.
The larger costs are the ones the Financial Consumer Agency of Canada lists: appraisal, title search, title insurance and legal fees, plus any lender and broker fees. Our consolidation page shows how those fees can eat the first year of savings.
What Alberta law means if payments fail
Alberta’s Law of Property Act, section 40, says that for an action on a mortgage of land the lender’s right is restricted to the land and to foreclosure, and no action lies on the covenant to pay. Section 43 carves out mortgages given by corporations, so the rule does not read the same for a company that owns the home. Section 41 sets a redemption period of six months from the order for land other than farm land, which a court can shorten or extend.
None of that makes a second mortgage safe. It means the home is what is at risk, and a lawyer should explain how the sections apply to your file.
Renewal payments in a city of mixed districts
The Bank of Canada’s 2026 Financial Stability Report says the last of the pandemic-era five-year fixed-payment mortgages renew over the next twelve months with payments up about 15%, and that nearly all large increases will have passed by the second half of 2027. It names no Alberta figure. If your first mortgage renews soon, price a renewal or a bank refinance before you add a second charge.
Reading the district gap before you ask for a number
The distance between Calgary’s cheapest and dearest detached districts is large. In October 2026 the City Centre benchmark of $992,500 was $444,500 above the North East benchmark of $548,000, and the East sat lower still at $463,800. A lender does not average those. It looks at recent sales of homes like yours, close to yours, and the appraisal for your address decides the number.
Before you phone anyone, collect the documents a lender will ask for: your latest property tax notice, the current mortgage statement showing the balance and the renewal date, a list of the debts you want cleared with their balances, and proof of income. Having them ready speeds up the one thing you control, which is how clearly your file reads.
If the numbers on your own file come out close to the ceiling, as in the North East example, ask whether a smaller loan, a longer wait or a bank option would serve you better.
Licence first, then the HELOC comparison
The Real Estate Council of Alberta licenses mortgage brokers, and a licence is required of anyone who deals in mortgages for others for pay, with limited exemptions. Ask for it and confirm it. Then read the HELOC or second mortgage comparison and the Alberta page for the rules across the province. If you would rather have a professional test your Calgary numbers, start with your options here.
A Calgary North East detached home at the October 2026 benchmark
The $548,000 value is CREB's October 2026 detached benchmark for the North East district, used as a stand-in for an appraised value. The $400,000 first mortgage and the $50,000 loan are made up. The 80% ceiling is the one the Financial Consumer Agency of Canada gives for a second mortgage.
- Home value used
- $548,000
- Owed on the first mortgage
- $400,000
- 80% of the home value
- $438,400
- Room under the ceiling before any loan
- $38,400
- Combined loan-to-value with a $50,000 loan
- 82.1%
- Amount a $50,000 loan overshoots the ceiling by
- $11,600
$548,000 x 0.80
$438,400 minus $400,000
$450,000 / $548,000
A Calgary West detached home with a large equity cushion
The $988,400 value is CREB's October 2026 detached benchmark for the West district, used as a stand-in for an appraised value. The $520,000 first mortgage and $120,000 loan are made up.
- Home value used
- $988,400
- 80% of the home value
- $790,720
- Room under the ceiling before any loan
- $270,720
- Combined loan-to-value with a $120,000 loan
- 64.8%
- Equity left after the loan
- $348,400
- Room left under the ceiling after the loan
- $150,720
$988,400 x 0.80
$790,720 minus $520,000
$640,000 / $988,400
$988,400 minus $640,000
Questions people ask
Calgary benchmark price: will it match what my own home is worth?
No. CREB's October 2026 benchmark of $564,200 blends every property type and district. The same report puts detached homes at $735,100 and apartments at $288,800. A lender orders its own appraisal of your address, and that figure is the one that counts.
Could a Calgary condo be harder to borrow against right now?
It can be. CREB reported the October 2026 apartment benchmark at $288,800, about 7.9% lower than a year earlier, and a falling value shrinks the room under a lender's ceiling. Some lenders also ask more questions about the building before they offer anything.
What if I owe more than the house is worth in Alberta: can a lender chase me?
For a mortgage given by an individual, Alberta's Law of Property Act section 40 restricts the lender to the land and to foreclosure, with no action on the covenant to pay. Corporations are treated differently under section 43, so a lawyer should confirm how it applies to you.
Registering a second mortgage in Calgary: what does Land Titles charge?
Since October 20, 2024 the registration levy is $5 for every $5,000 of the mortgage amount, on top of a flat fee set in the Tariff of Fees Regulation. We have not confirmed the flat fee, so ask your lawyer for the total.
Must a Calgary private second mortgage go through a licensed broker?
Anyone who deals in mortgages for another person for pay needs a mortgage broker licence from the Real Estate Council of Alberta, unless an exemption applies. You can search the licence before you hand over documents or money.
Sources
- CREB: Calgary Monthly Stats Package, October 2026, 2026-10
- Statistics Canada: Table 98-10-0002-01, Population and dwelling counts, 2021 Census
- Government of Alberta: Register a land title document or plan, 2024-10
- Alberta King's Printer: Law of Property Act, RSA 2000, c L-7, sections 40 and 41
- Real Estate Council of Alberta: Licence types, mortgage brokerage
- Financial Consumer Agency of Canada: Borrowing against your home equity