
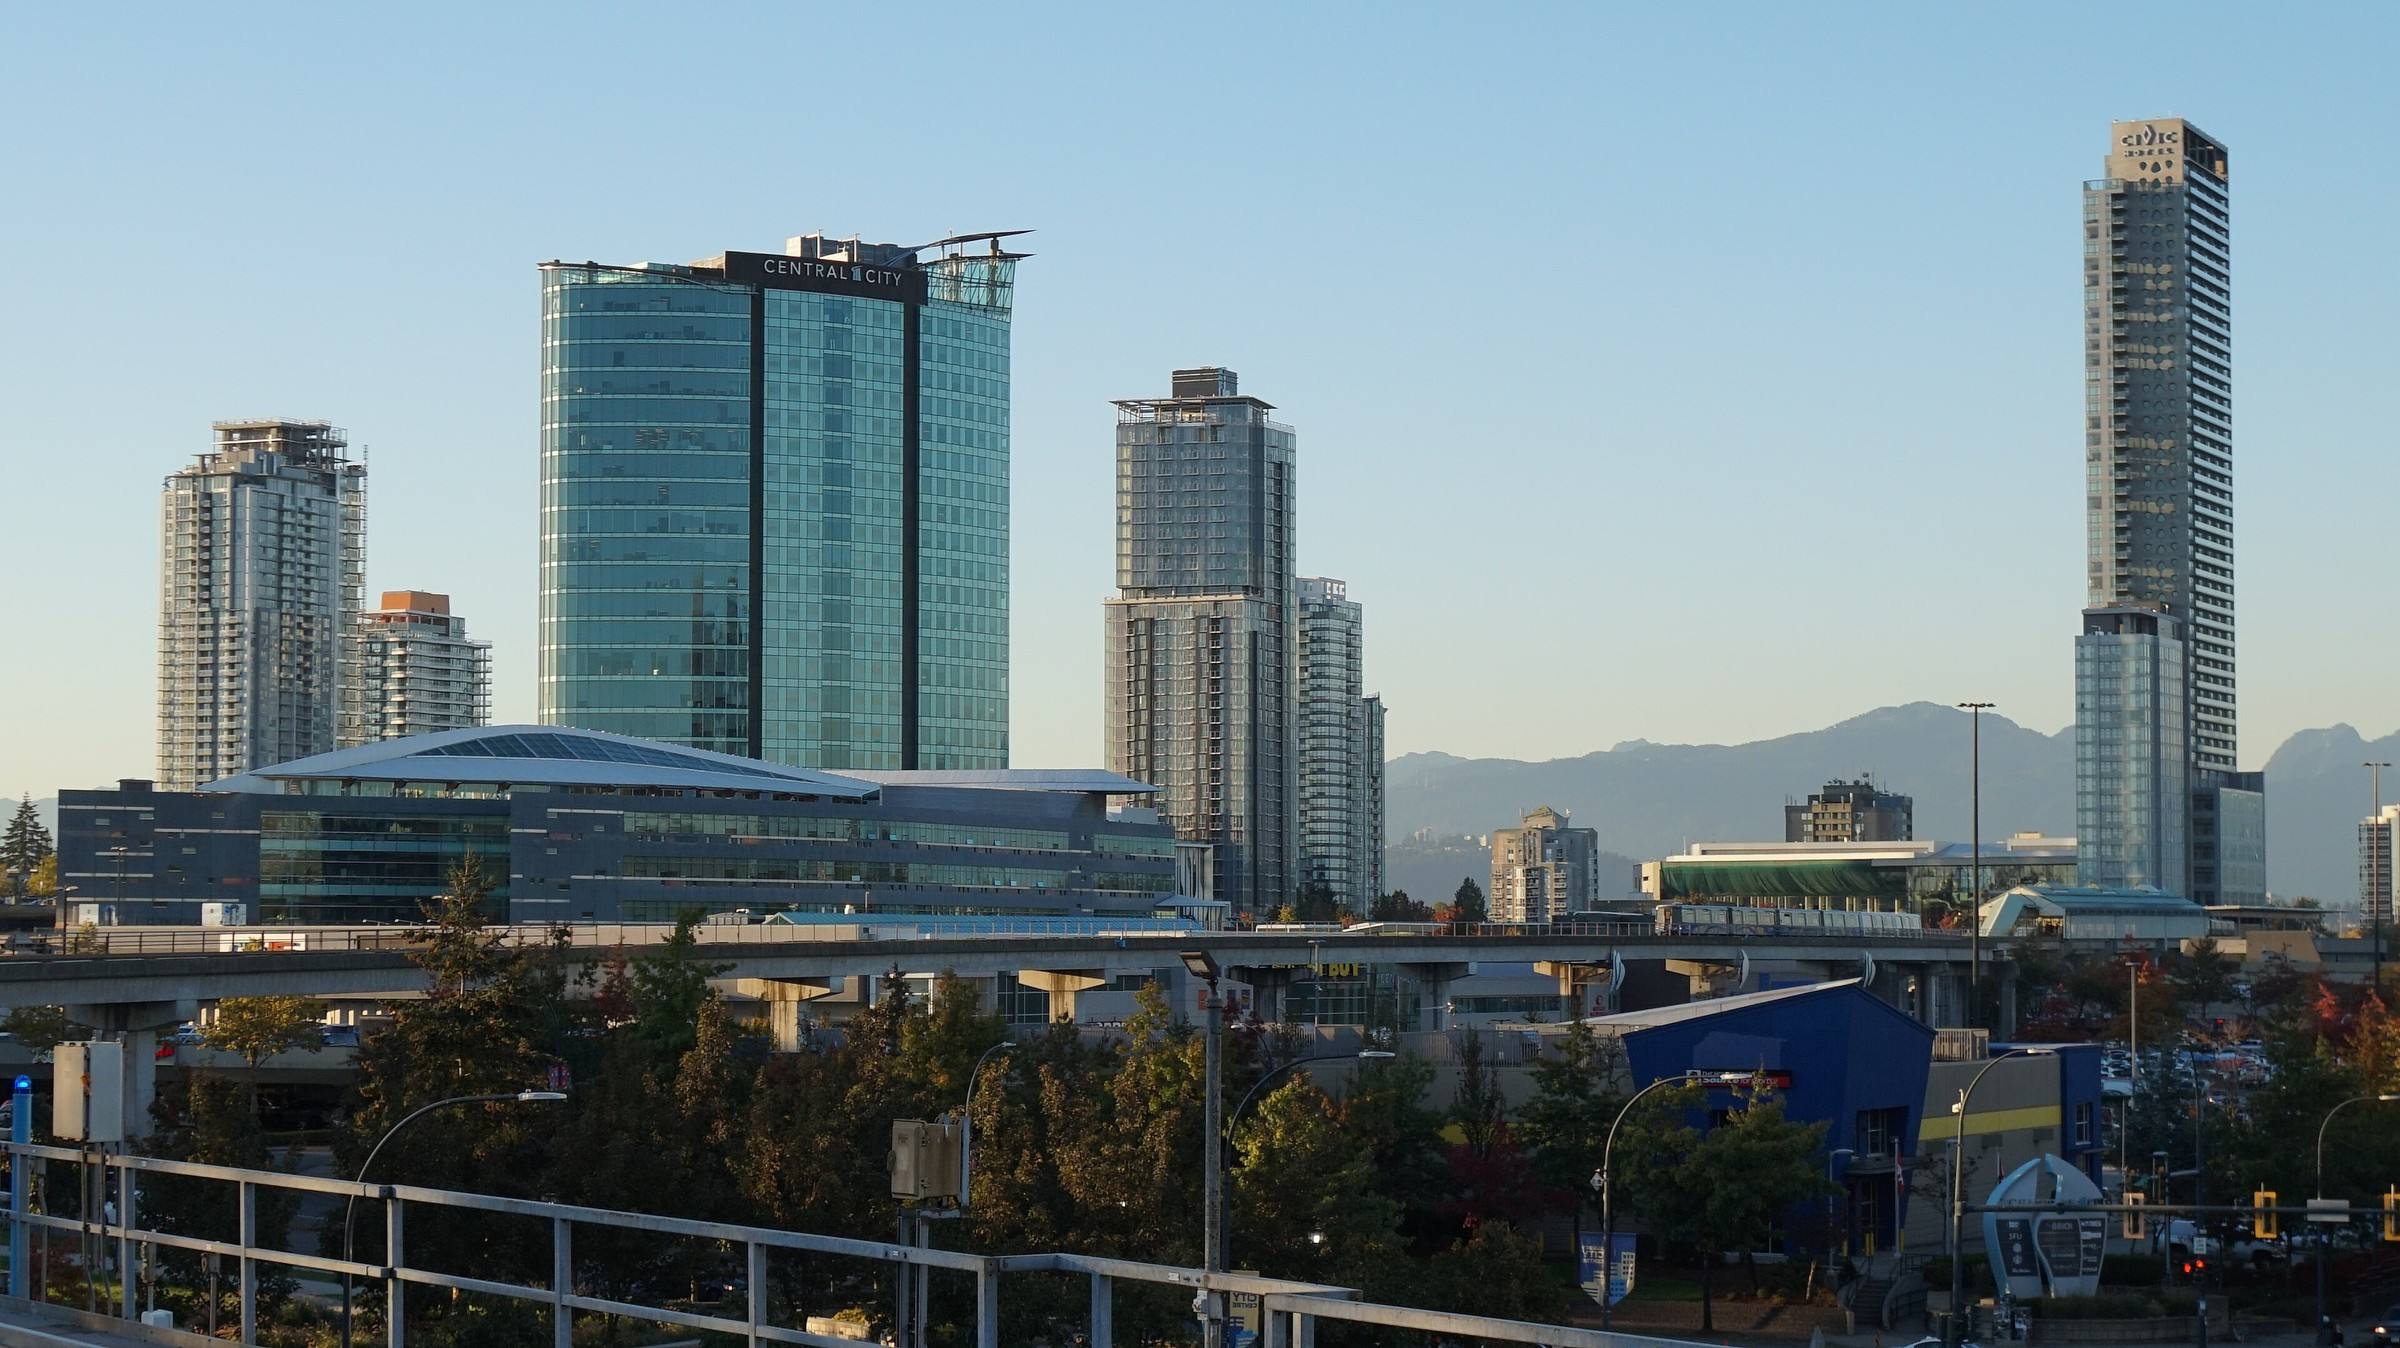

- Benchmark detached home, City of Surrey
- $1,380,100As of October 2026.Source
- Benchmark townhome, City of Surrey
- $757,300As of October 2026.Source
- Benchmark apartment, City of Surrey
- $443,900As of October 2026.Source
- Population of the City of Surrey
- 568,322As of 2021 Census.Source
On this page
Surrey is the biggest city in the Fraser Valley Real Estate Board’s territory, and it is where the last year’s price correction shows up most clearly in equity maths.
FVREB’s October release, read for Surrey equity
The Fraser Valley Real Estate Board reports the City of Surrey as its own area. In October 2026 its benchmark prices were $1,380,100 for a detached home, $757,300 for a townhome and $443,900 for an apartment. Against October 2025 those are drops of 7.7%, 5.5% and 9.6%. Surrey recorded 186 detached sales that month, 4.5% more than a year earlier, but 132 townhome sales were down 25.4% and 101 apartment sales were down 27.9%.
Across the whole board, FVREB reported a buyer’s market with a sales-to-active-listings ratio of 11%, and its chief executive said much of the pandemic-era price growth has been erased. Surrey’s census population reached 568,322 in 2021, a 9.7% increase on 2016, so there are a lot of owners who bought into the rise.
Surrey equity versus Surrey room
The first example above shows a detached owner with plenty of room today and about $92,000 less than a year ago. The second shows how the 80% rule bites on a condo: $113,900 of equity, $25,120 of lendable room. The Financial Consumer Agency of Canada is the source of the rule: 80% of appraised value, less your mortgage balance, is the second mortgage limit.
That is why a quote based on last year’s value can fall apart at appraisal. Ask any broker what value they are using and whether it comes from an appraisal. Work your own figures through the calculator first.
What a court-ordered sale looks like in BC
Surrey owners who fall behind face a court process, not a quick sale. Legal Aid BC says that no matter what the mortgage contract says, a lender in BC cannot sell your home without your consent or a court order. The lender files a petition. If the court grants an Order Nisi, it sets the redemption period, usually six months, and includes a judgment for the amount owed. The lender can then ask for an Order for Conduct of Sale, and any sale needs a court order approving it. Courts usually allow around 30 days after that order takes effect to move out.
If the sale does not cover the debt, Legal Aid BC says the lender can have an enforceable judgment for the shortfall and may try to collect for up to 10 years. If this is your situation, speak to a lawyer or Legal Aid BC first, and read our page on mortgage arrears. A second mortgage can sometimes bring a mortgage current, but only if the numbers work and the lender agrees.
Transfer tax and other costs
Property transfer tax applies when you purchase or gain an interest in property registered at the Land Title Office, at 1% on the first $200,000, 2% up to $2,000,000 and 3% above that. The government page lists foreclosures among the taxable transactions and does not mention mortgages, so a loan against a home you keep is not a purchase. Your costs are the lender fee, any broker fee, legal costs and an appraisal. Our bad credit page and self-employed page show how income and credit change the price lenders ask.
Rates and where to look next
FVREB’s chief executive said that with interest rates recently moving higher and possibly more increases ahead, borrowing costs are now part of every decision. We found no Surrey-specific renewal or arrears figure, so we do not give one. If you only need to lower a payment, a bank refinance may cost less than adding a second loan, and the refinance page explains the difference.
Surrey’s three sub-areas differ
FVREB also reports Surrey in parts. For detached homes in October 2026 the benchmark was $1,288,000 in Surrey Central, down 8.9%, $1,326,400 in Cloverdale, down 6.0%, and $1,254,500 in North Surrey, down 9.8%. Apartments were $453,600 in Central, $501,800 in Cloverdale and $392,300 in North Surrey, which fell 10.2%.
North Surrey’s 52 apartment sales were down 32.5% on the year, and its 656 active apartment listings are a large pool for any buyer, or any appraiser, to compare against. If you own a condo there, expect a lender to look at recent nearby sales rather than the City-wide figure.
Having a Surrey file looked at
Ask a licensed mortgage professional in British Columbia to line up a bank, a credit union and private lenders and say what the appraisal needs to show. The British Columbia page has the provincial rules. For a professional’s view of your Surrey numbers, go through your options.
A Surrey detached home at the October 2026 benchmark
The $1,380,100 value is FVREB's October 2026 benchmark for a detached home in the City of Surrey, used as a stand-in for an appraisal. The $850,000 first mortgage and $120,000 new loan are made up. The 80% ceiling is the Financial Consumer Agency of Canada's figure for a second mortgage.
- Home value used
- $1,380,100
- Owed on the first mortgage
- $850,000
- Combined loan-to-value with a $120,000 loan
- 70.3%
- 80% of the home value
- $1,104,080
- Room under an 80% ceiling before the loan
- $254,080
$970,000 divided by $1,380,100
A Surrey apartment at the October 2026 benchmark, with a small loan
The $443,900 value is FVREB's October 2026 benchmark for an apartment in the City of Surrey, used as a stand-in for an appraisal. The $330,000 first mortgage and $25,000 loan are made up.
- Home value used
- $443,900
- Equity before the new loan
- $113,900
- 80% of the home value
- $355,120
- Room under an 80% ceiling before the loan
- $25,120
- Room left after a $25,000 loan
- $120
$443,900 minus $330,000
$355,120 minus $330,000
Questions people ask
How do Surrey's price drops affect a loan on my house?
FVREB's October 2026 benchmark for a City of Surrey detached home was $1,380,100, down 7.7% from $1,495,300 a year earlier. A lender values your home today, so the same mortgage balance now leaves less room under an 80% ceiling than it did last year.
In BC, can my Surrey lender sell my house without going to court?
In BC, Legal Aid BC says a lender cannot sell your home without your consent or a court order, whatever the mortgage contract says. The lender starts a court action, and a judge sets the terms, including how long you have to pay it out.
What is the redemption period in a BC foreclosure?
Legal Aid BC says the court usually sets it at six months, though it can be shorter, for example when the amount owed is roughly equal to or more than the property is worth. During it you can pay the full amount owed plus interest and legal costs.
Does a Surrey condo make a second mortgage harder to get?
It can be thinner on room. FVREB's October 2026 apartment benchmark for the City of Surrey was $443,900, and 80% of that is $355,120, so even a $330,000 first mortgage leaves little. Lenders also check strata fees and special levies.
Sources
- Fraser Valley Real Estate Board: Statistics Package, October 2026, 2026-11
- Statistics Canada: Census Profile, 2021 Census of Population, Surrey, City (CY) [Census subdivision]
- Legal Aid BC: Can't Pay Your Mortgage?
- Financial Consumer Agency of Canada: Borrowing against your home equity
- Government of BC: Property transfer tax