
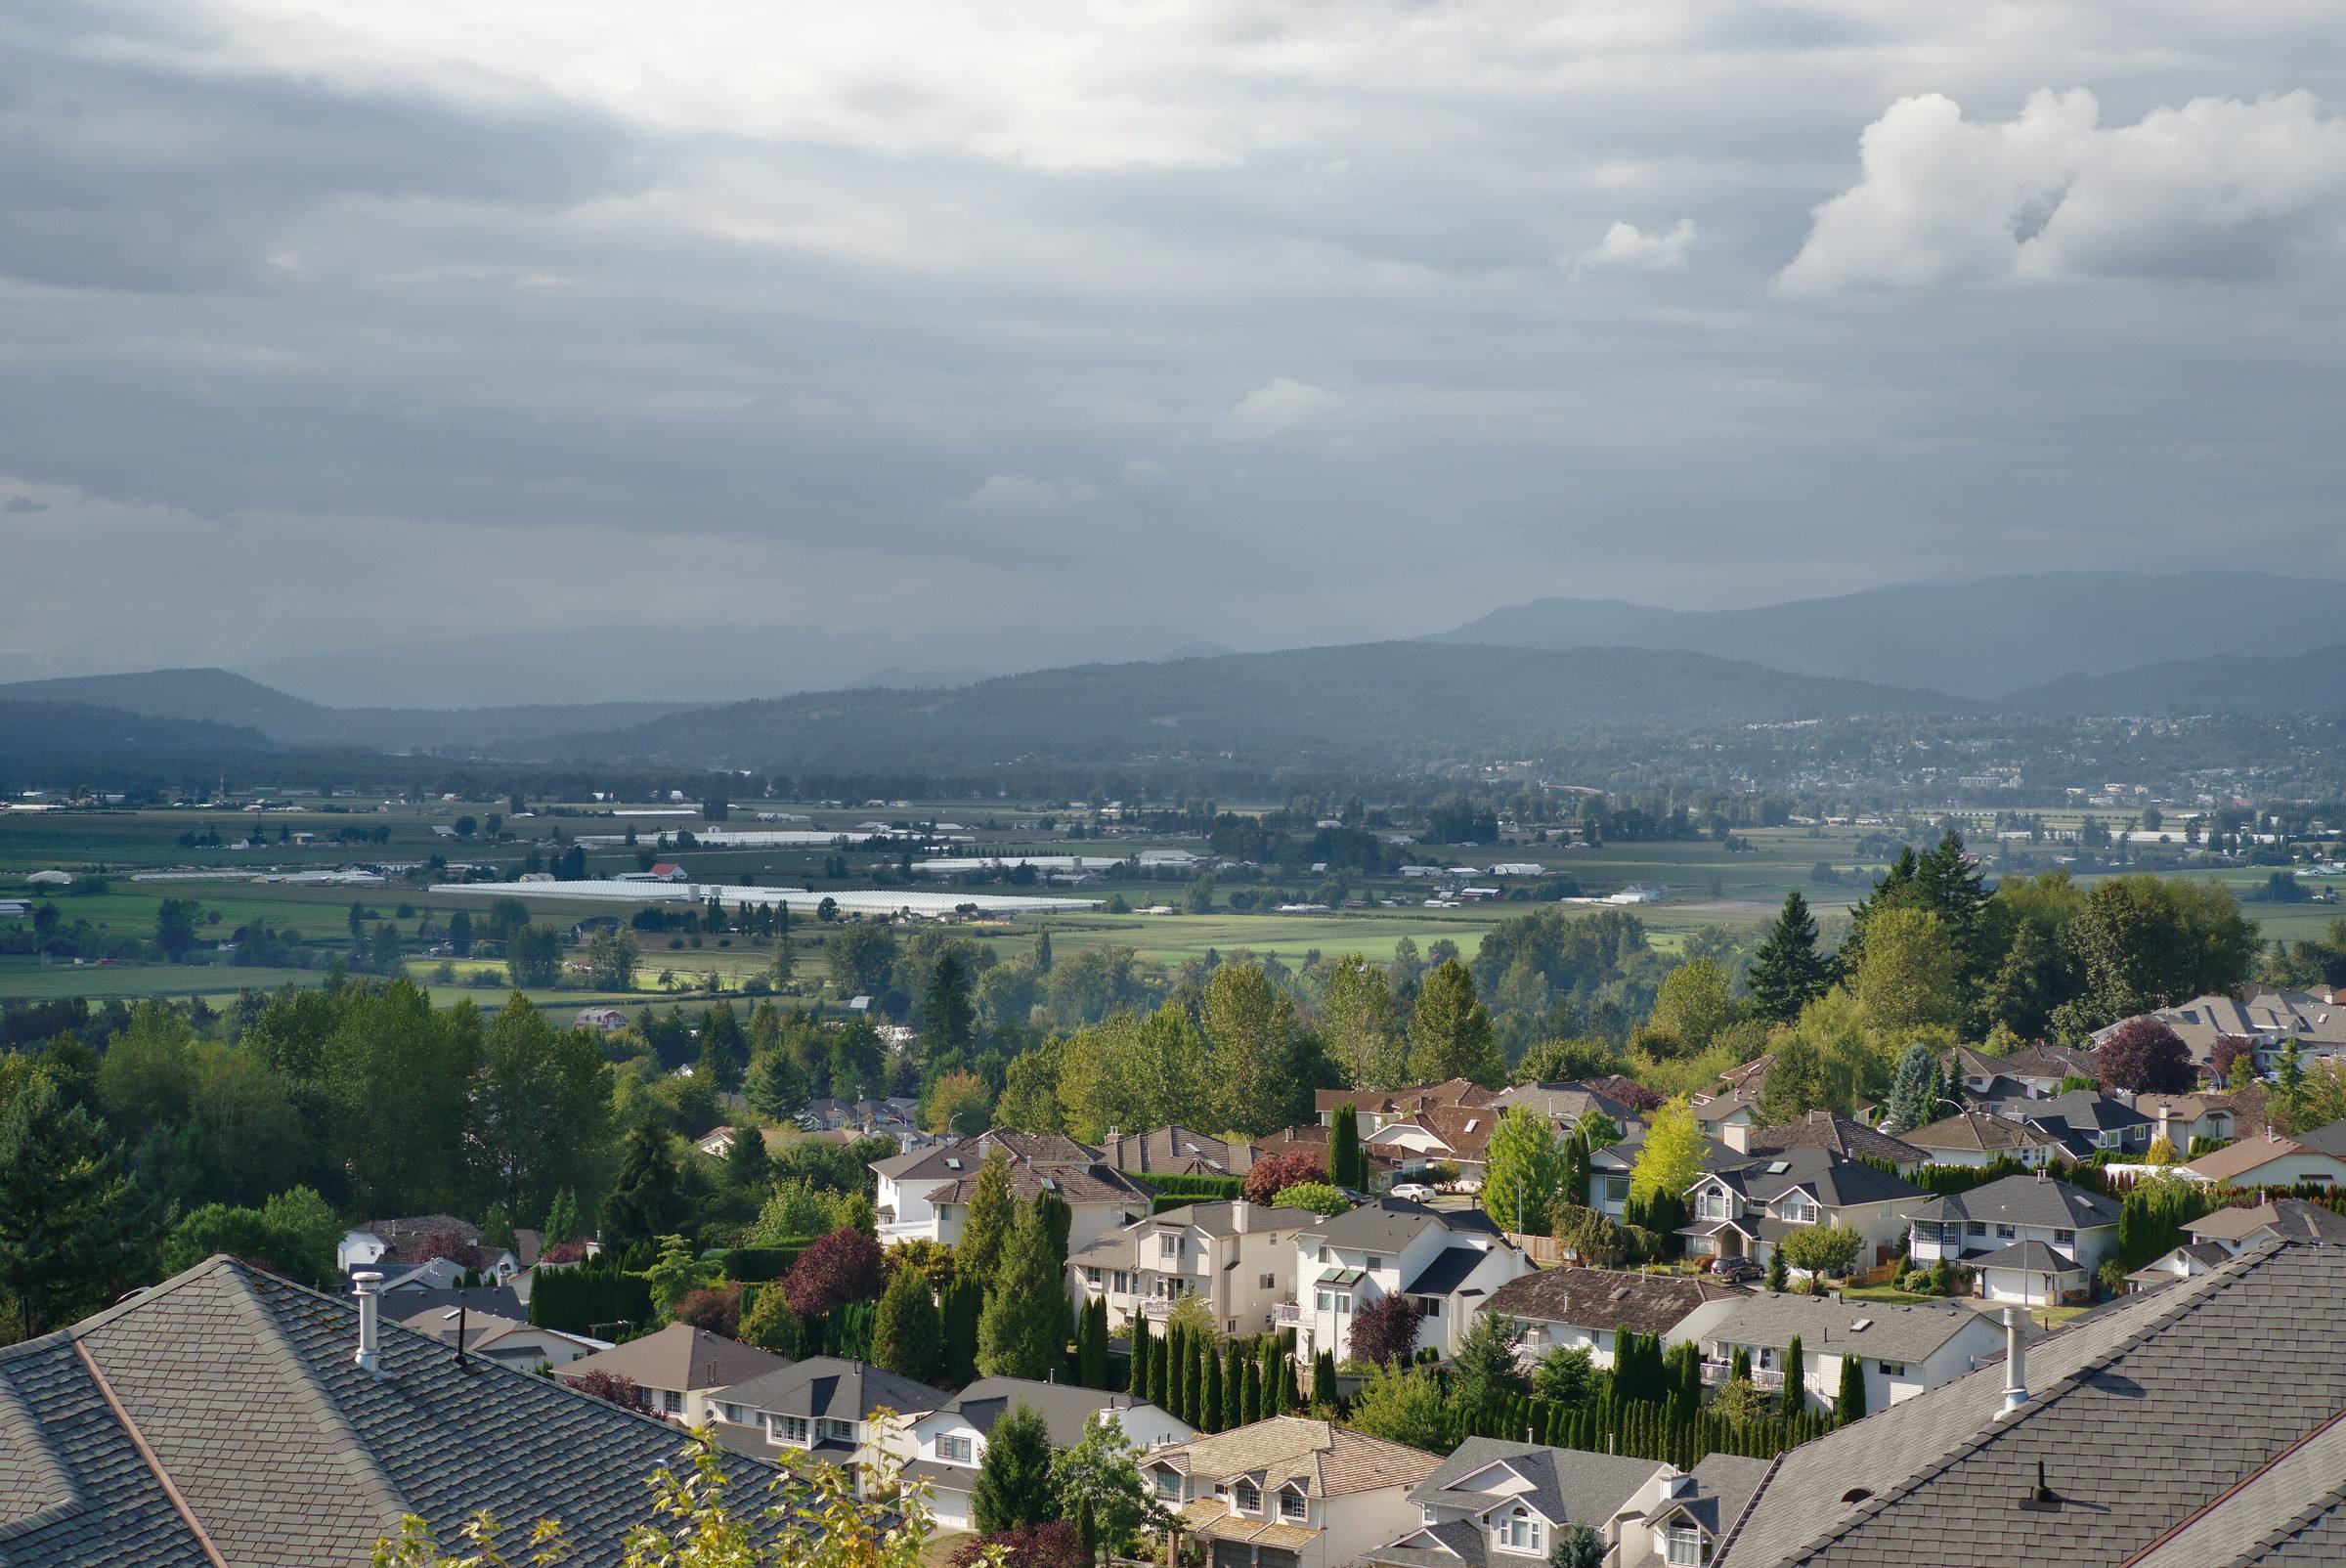

- Benchmark detached home, Abbotsford
- $1,090,500As of October 2026.Source
- Benchmark townhome, Abbotsford
- $579,600As of October 2026.Source
- Benchmark apartment, Abbotsford
- $370,300As of October 2026.Source
- Median detached sale price, Abbotsford
- $1,060,000As of October 2026.Source
- Population of the City of Abbotsford
- 153,524As of 2021 Census.Source
On this page
Abbotsford sits at the eastern end of the Fraser Valley Real Estate Board’s area, and its detached prices have come down faster than most of the Lower Mainland.
How far the Abbotsford benchmark has slipped
In October 2026 FVREB put the Abbotsford detached benchmark at $1,090,500, down from $1,254,600 a year before. The townhome benchmark was $579,600, down 10.1%, and the apartment benchmark was $370,300, down 10.0%. The median detached sale price that month was $1,060,000, and 72 detached homes sold, up from 54 a year earlier.
Across the Fraser Valley the board reported a buyer’s market with a sales-to-active-listings ratio of 11%, and about 50 days on average to sell a detached home. Abbotsford’s population rose 8.6% between 2016 and 2021, from 141,397 to 153,524, so many owners are relatively recent buyers who bought nearer the top.
A falling value cuts equity and room together
A falling market shows up twice. First, your equity is smaller. Second, the ceiling the Financial Consumer Agency of Canada describes, 80% of appraised value less your mortgage balance, shrinks along with the value. The first example above shows an owner who has lost $164,100 of equity and holds $72,400 of lendable room. The second shows a townhome owner with $63,680. Use the calculator with a value a little below the benchmark, so the plan survives a low appraisal.
What happens if the loan goes wrong
Abbotsford owners with thin equity should know the enforcement path. Legal Aid BC says a BC lender cannot sell your home without your consent or a court order, whatever the contract says. If the amount owed is about equal to or more than the property is worth, the court is likely to set a redemption period shorter than the usual six months. A second mortgage adds a second lender who can start its own action. Read the power of sale page for how enforcement works elsewhere in Canada, and speak to a lawyer before you take on a loan you may not be able to repay.
Rural property, self-employment and debt
Abbotsford has farms and acreage, and its homeowners often run their own businesses. A benchmark describes a typical detached home, so an acreage owner should not lean on it. Lenders treat rural land and farm use differently, and our page on second mortgages on rural property explains what they ask. If your income is self-employed, see the self-employed page.
If you are borrowing to clear debt, remember that fees come out of the loan. Our consolidation page shows how to work out the break-even.
The bill for borrowing, and the rate backdrop
A second mortgage carries interest, a lender fee, often a broker fee, legal costs and an appraisal. BC’s property transfer tax is a tax on purchases, and we found no line for a loan on a home you keep. FVREB’s chief executive said that with interest rates recently moving higher and possibly rising further, buyers must consider borrowing costs, and the same applies to anyone adding a loan. We did not find an Abbotsford-specific arrears or renewal number, so we give none.
Reading a falling market as a borrower
Abbotsford’s drop is worth reading carefully. A benchmark that fell $164,100 in a year, 13.1% for detached homes, means appraisals can lag behind the most recent sales, and a lender may order a fresh valuation rather than accept an older one. If you bought a home in 2024 or early 2025, your purchase price may be above today’s value.
A practical test is to subtract 10% from the benchmark, run the 80% rule again and see whether the plan still works. If it does not, a smaller loan, a longer wait or a different route such as a bank renewal may be wiser than pushing a thin file through.
How long homes take to sell
FVREB reports that across its whole area in October 2026 a detached home took 50 days on average to sell, a condo 44 days and a townhome 37 days. Those are board-wide figures, not Abbotsford’s alone. A lender thinks about this when it asks how quickly it could recover its money if a loan went wrong, which is one reason some lenders cap the loan at a lower share of value in slower segments.
Testing a plan against a lower appraisal
A licensed mortgage professional in British Columbia can run your plan against a lower value and set banks, credit unions and private lenders side by side. The British Columbia page covers the provincial rules. For a second look at your Abbotsford figures, check where you stand.
An Abbotsford detached owner whose equity shrank in a year
The $1,254,600 and $1,090,500 values are FVREB's October 2025 and October 2026 Abbotsford detached benchmarks. The $800,000 first mortgage and $50,000 new loan are made up. The 80% ceiling is the Financial Consumer Agency of Canada's figure for a second mortgage.
- Equity at the October 2025 benchmark
- $454,600
- Equity at the October 2026 benchmark
- $290,500
- 80% of the October 2026 value
- $872,400
- Combined loan-to-value with a $50,000 loan
- 77.9%
- Room under an 80% ceiling before the loan
- $72,400
$1,254,600 minus $800,000
$1,090,500 minus $800,000
$850,000 divided by $1,090,500
An Abbotsford townhome at the October 2026 benchmark
The $579,600 value is FVREB's October 2026 Abbotsford townhome benchmark, used as a stand-in for an appraisal. The $400,000 first mortgage and $40,000 loan are made up.
- Home value used
- $579,600
- Equity before the new loan
- $179,600
- Combined loan-to-value with a $40,000 loan
- 75.9%
- 80% of the home value
- $463,680
- Room left after the new loan
- $23,680
- Room under an 80% ceiling before the loan
- $63,680
$579,600 minus $400,000
$440,000 divided by $579,600
$63,680 minus $40,000
Questions people ask
By how much has the Abbotsford detached benchmark fallen?
FVREB's benchmark for an Abbotsford detached home was $1,090,500 in October 2026, against $1,254,600 in October 2025, a fall of $164,100 or 13.1%. Townhomes fell 10.1% to $579,600 and apartments fell 10.0% to $370,300 over the same twelve months.
When might a short redemption period apply to my Abbotsford home?
Legal Aid BC says the court usually sets six months, but a shorter period is likely when the amount owed is roughly equal to or more than the property's value. That is why falling prices raise the stakes for owners with little equity.
Are acreage and farm properties around Abbotsford treated differently by lenders?
Often, yes. Lenders may treat rural land, outbuildings and farm use differently from a city lot, and a benchmark describes a typical detached home, which an acreage rarely is. Ask a lender early what they will count and what their appraiser needs.
Self-employed in Abbotsford: is a second mortgage on stated income possible?
Some private lenders accept income that banks discount, but they usually weigh the equity and charge more. Expect to show how the loan will be repaid. Be careful with any lender who does not ask about it at all.