
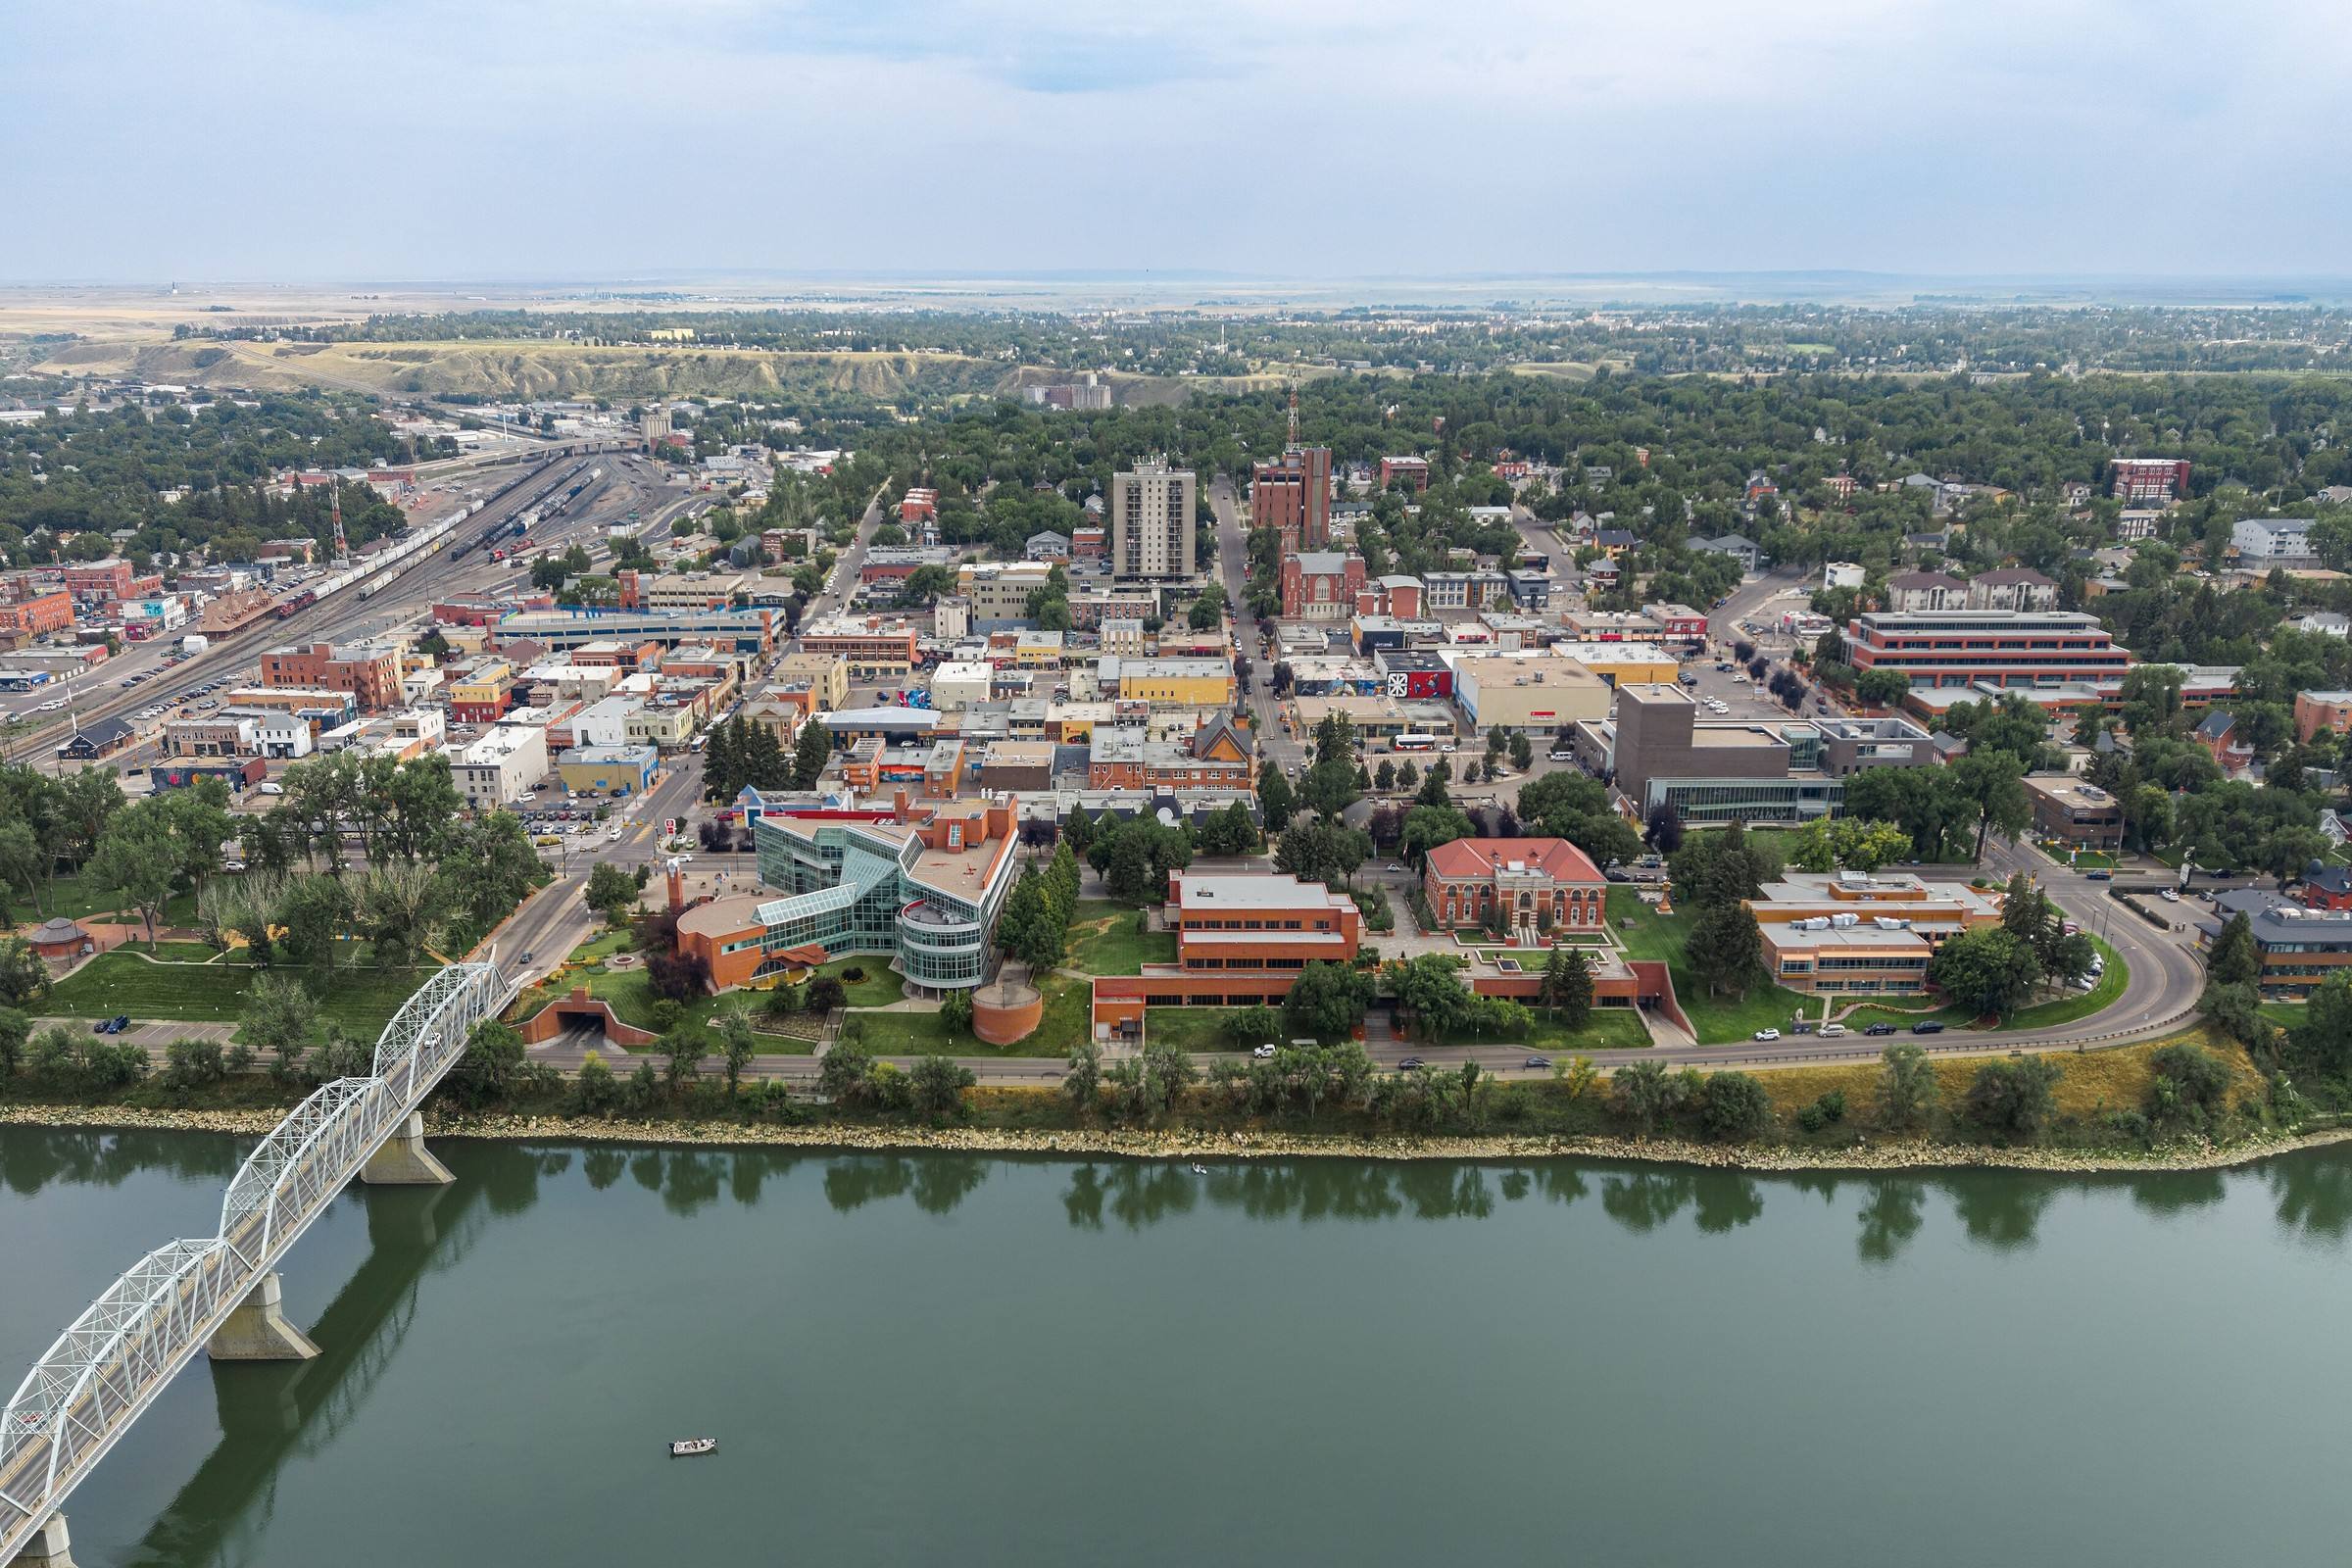

- Average residential price, City of Medicine Hat
- $429,533 (up 8.7%)As of October 2026.Source
- Average detached price, City of Medicine Hat
- $475,935 (up 10.4%)As of October 2026.Source
- City inventory change, year over year
- up 24.8% to 166 unitsAs of October 2026.Source
- Population of Medicine Hat
- 63,271As of 2021 Census.Source
On this page
Medicine Hat is a smaller city where a typical house costs well under what it would in Calgary. Its market is small enough that one month’s sample can look odd, so read each average with the number of sales behind it.
Medicine Hat’s October averages, read for equity
The Alberta Real Estate Association’s October 2026 sheet for the City of Medicine Hat records 97 residential sales, up 1% on October 2025, and 166 listings in inventory, up 24.8%. The average price of a residential sale was $429,533, up 8.7%. Detached homes made up 74 of the sales and averaged $475,935, up 10.4%. Apartments averaged $262,489 (up 12%) on 14 sales, while semi-detached homes ($354,250) and row homes ($249,850) were each down 11.3% on 5 and 4 sales. Months of supply were 1.71.
From January to October the all-residential average was $398,005, up 7%, on 943 sales, down 3%.
Medicine Hat’s population stood at 63,271 in 2021, unchanged from 63,260 in 2016. A city without population growth relies on the people who already live there, and what you can borrow depends on your own home.
The ceiling, not the equity, sets the limit
The Financial Consumer Agency of Canada puts the limit for a second mortgage at 80% of appraised value minus the mortgage balance. At the city average, a $250,000 first mortgage leaves $93,626 and a $40,000 loan leaves $53,626. At a detached value of $475,935, a $400,000 first mortgage is already past the ceiling by $19,252.
The point is not that either owner is in trouble. It is that the ceiling is set by the value, and an owner with $75,935 of equity can have no room at all. Run the calculator with your actual mortgage balance before you decide how much you need.
Registration, appraisal and legal bills
Alberta has no land transfer tax on a purchase, and registering a second mortgage on a home you already own is not a purchase. The Government of Alberta charges a registration levy of $5 for every $5,000 on mortgages received on or after October 20, 2024. For a $40,000 loan that is 8 units, so $40, plus a flat fee we could not confirm from the government page.
Appraisal, title search, title insurance and legal fees are the larger part, as the Financial Consumer Agency of Canada lists. On a small loan, fixed costs can be a big share of the amount.
Farm, acreage and business owners
Many households in and around a city this size own land outside the city limits, or run a business from home. Both change how a lender looks at the file. Land outside the city is often valued differently, and Alberta’s Law of Property Act treats farm land separately from other land, so a lawyer should explain the position. Read second mortgages on rural property before you assume the city average applies.
If the loan is for a business, a lender will ask about the income, and a failed business can put the home at risk. Compare business purpose second mortgages with a business loan that does not use the house. If you are considering a first mortgage from a private lender, see private first mortgages.
Why the dollar room is smaller in a smaller market
A percentage ceiling does not care what the city is. An 80% limit on a $429,533 value is $343,626, while the same limit on the Calgary West detached benchmark of $988,400 is $790,720. That is why borrowers in a smaller city often find that a plan that worked on a spreadsheet leaves too little to clear a large debt after a first mortgage is taken off.
If your need is large and your room is small, the honest answers are a smaller loan, a longer plan to pay down other debts, or a different route. A Licensed Insolvency Trustee or a credit counsellor can describe options that do not add a charge on your home.
The sheet covers sales inside the city only. Check which side of the city limit your property is on before you quote any number to a lender.
Who to ask in Medicine Hat
Under Alberta rules, the person who deals in mortgages for you for pay should hold a licence from the Real Estate Council of Alberta, with some exemptions. Ask to see it and check it. The Alberta page covers provincial rules, and a professional can go through your Medicine Hat numbers if you ask for a review of your options.
A Medicine Hat home at the October 2026 city average, with a $40,000 loan
The $429,533 value is the October 2026 average residential price in the City of Medicine Hat from the Alberta Real Estate Association, used as a stand-in for an appraised value. The $250,000 first mortgage and the $40,000 loan are made up. The 80% ceiling is the one the Financial Consumer Agency of Canada gives for a second mortgage.
- Home value used
- $429,533
- 80% of the home value
- $343,626
- Room under the ceiling before any loan
- $93,626
- Combined loan-to-value with a $40,000 loan
- 67.5%
- Room left under the ceiling after the loan
- $53,626
$429,533 x 0.80, rounded to the dollar
$343,626 minus $250,000
$290,000 / $429,533
A Medicine Hat detached home at the October 2026 average with a larger first mortgage
The $475,935 value is the October 2026 average detached price in the City of Medicine Hat from the Alberta Real Estate Association, used as a stand-in for an appraised value. The $400,000 first mortgage is made up.
- Home value used
- $475,935
- Owed on the first mortgage
- $400,000
- Loan-to-value of the first mortgage alone
- 84.0%
- 80% of the home value
- $380,748
- Amount the first mortgage already exceeds the ceiling by
- $19,252
$400,000 / $475,935
$475,935 x 0.80
Questions people ask
Which month do the Medicine Hat figures describe?
October 2026, from the Alberta Real Estate Association's monthly sheet for the City of Medicine Hat, published in early November. Prices and inventory change every month, so treat the numbers as a guide and ask a lender for a current appraisal.
Would the city average describe a home outside Medicine Hat?
Not reliably. The Alberta Real Estate Association sheet covers sales inside the City of Medicine Hat only. A property in the county, on an acreage or on farm land can be valued on a different basis, so the city average is the wrong comparison and your appraisal will say more.
Are more homes listed in Medicine Hat than a year ago?
Yes, from a low base. October inventory was 166 units, up 24.8%, while new listings fell 19% and sales rose 1%. Months of supply were 1.71. More listings give buyers choice, which can make a lender cautious about how fast a home would sell.
Farm or acreage near Medicine Hat: can I borrow against it?
Rural land is treated differently by lenders and by Alberta law, including a longer redemption period for farm land. Appraisals take longer and fewer lenders take them. Read our rural property page and speak to a lawyer first.
Do business owners use a Medicine Hat home to fund the business?
Some do, but it puts the family home behind a business risk. A lender will want to see the business income and a plan to repay. Read our business purpose page and weigh it against a business loan that does not use the house.
Sources
- Alberta Real Estate Association: City of Medicine Hat Monthly Statistics, October 2026 (MLS data via Pillar 9), 2026-11
- Statistics Canada: Table 98-10-0002-01, Population and dwelling counts, 2021 Census
- Government of Alberta: Register a land title document or plan, 2024-10
- Alberta King's Printer: Law of Property Act, RSA 2000, c L-7, section 41 (farm land redemption)
- Real Estate Council of Alberta: Licence types, mortgage brokerage
- Financial Consumer Agency of Canada: Borrowing against your home equity