

- Single-family benchmark, Kamloops
- $659,100As of September 2026.Source
- Townhome benchmark, Kamloops
- $511,900As of October 2026.Source
- Condo benchmark, Kamloops
- $359,200As of October 2026.Source
- Population of the City of Kamloops
- 97,902As of 2021 Census.Source
On this page
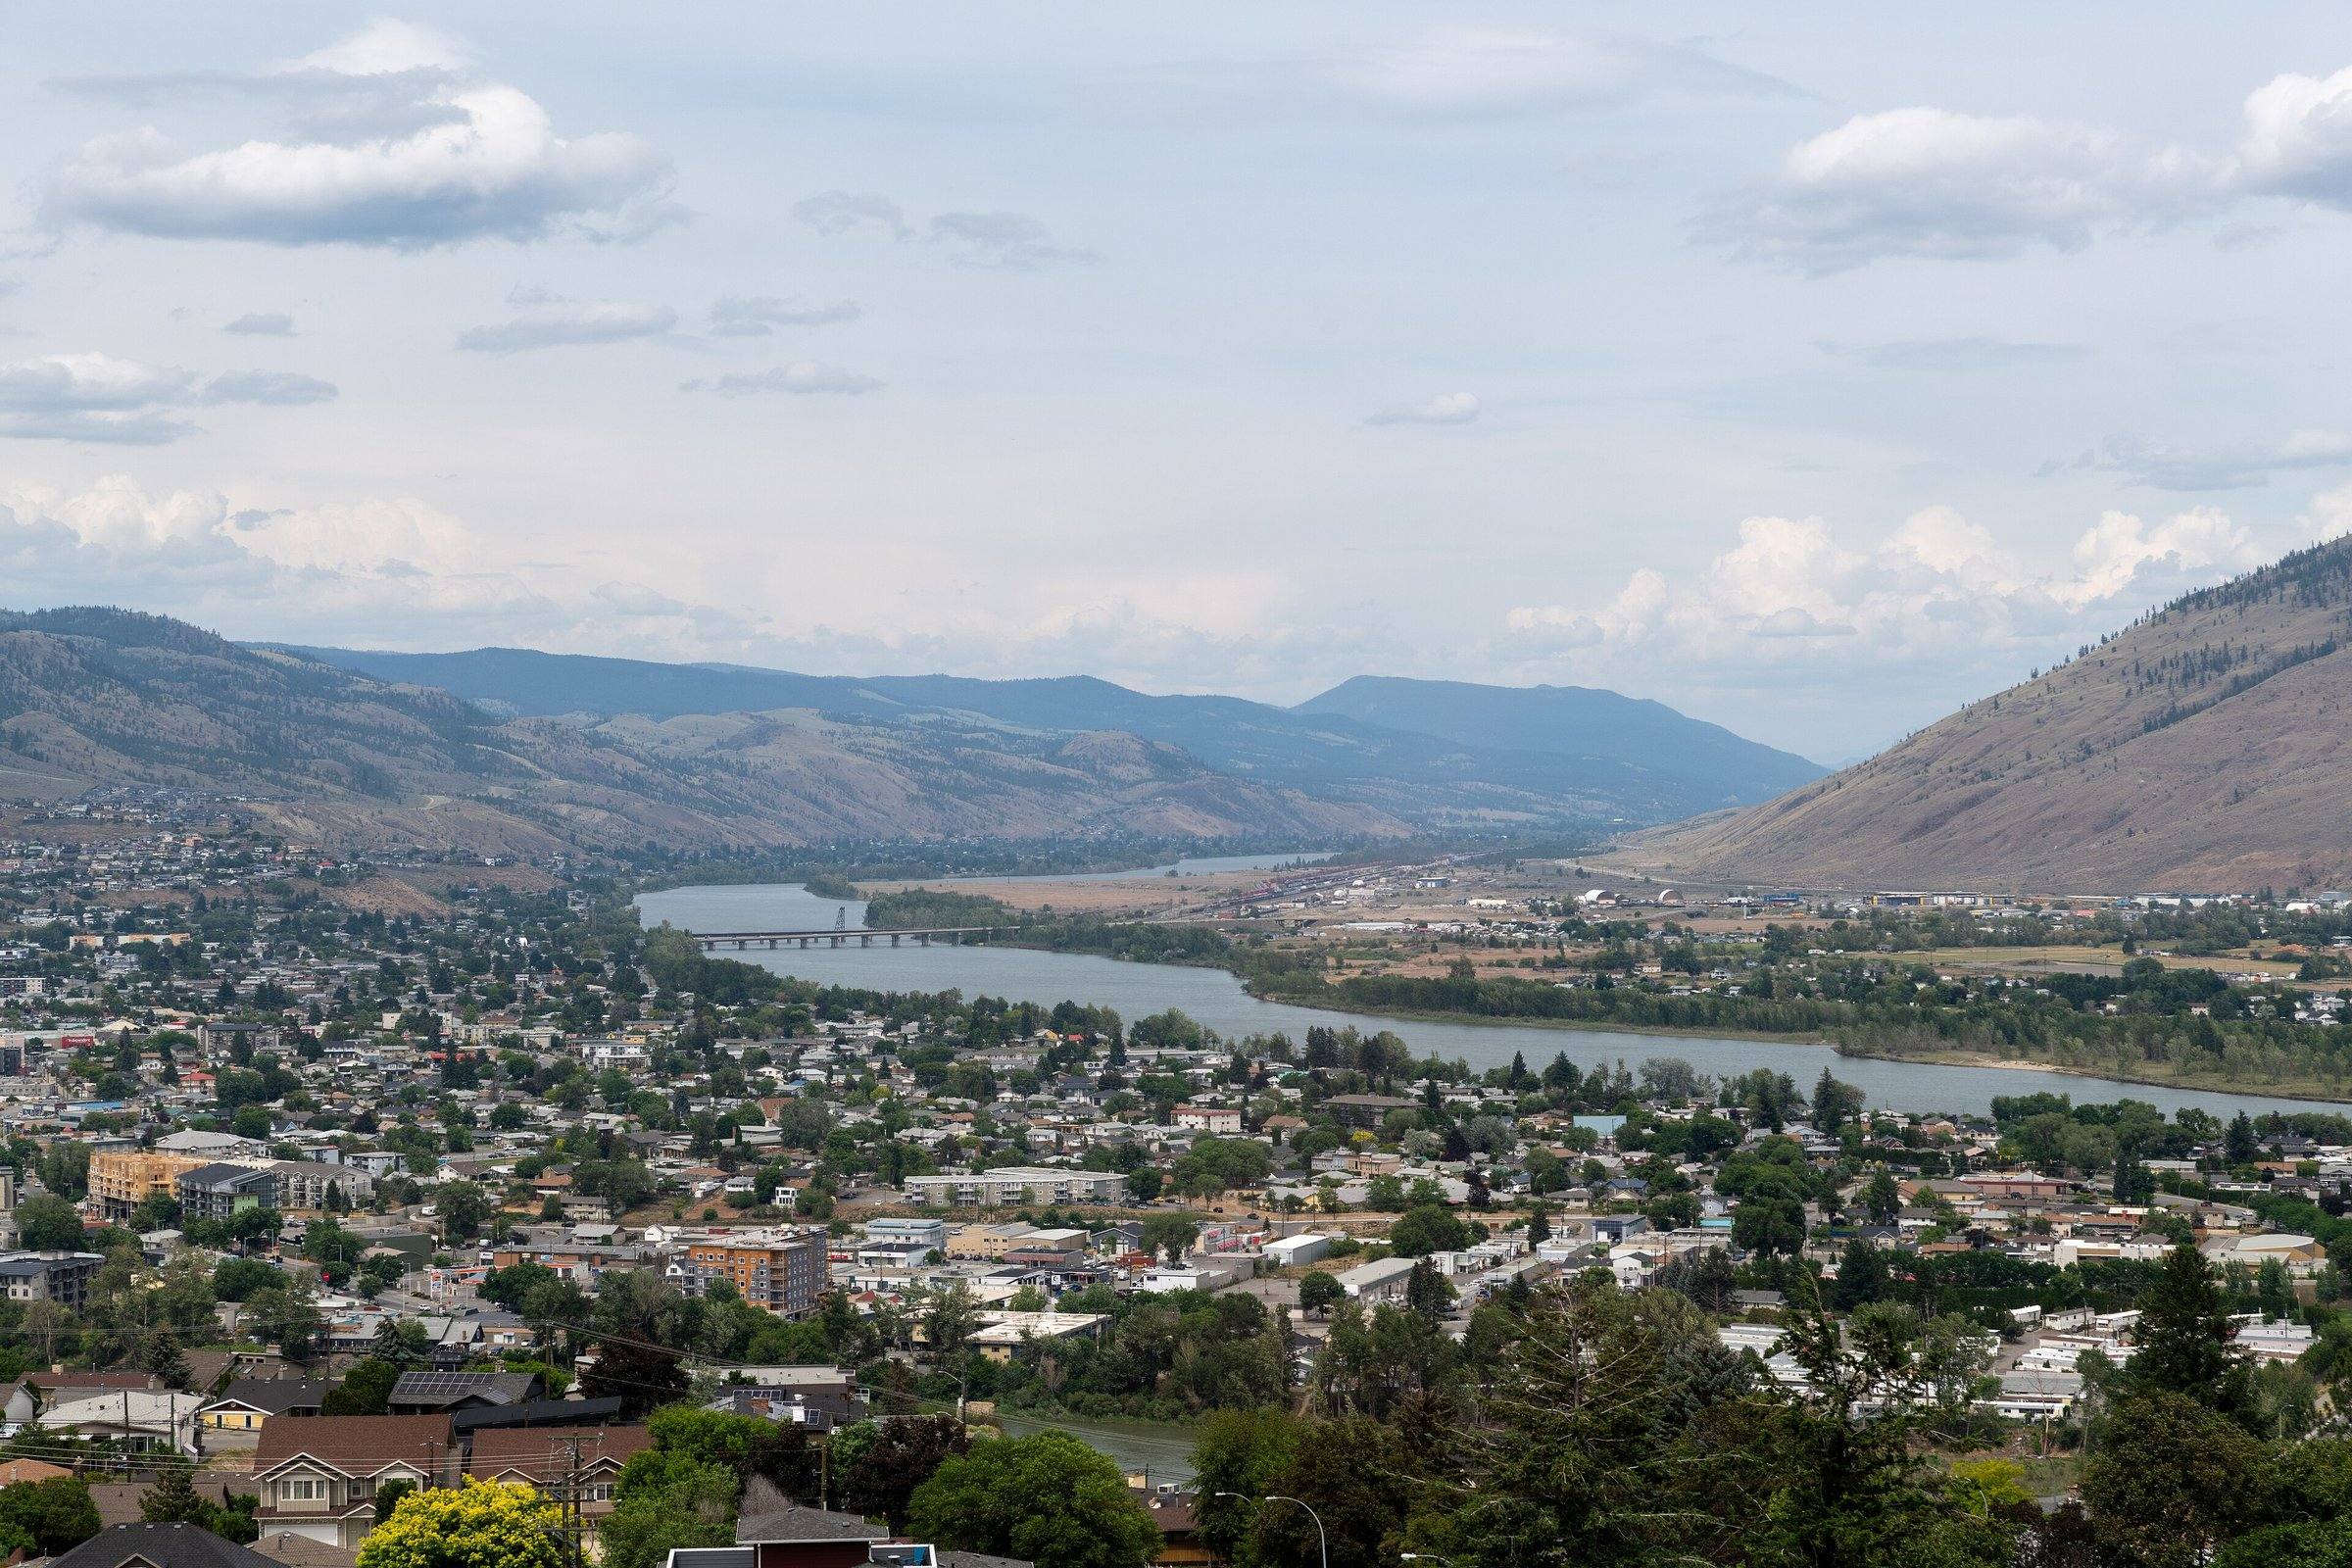
Kamloops is the largest city in the Thompson region, and its home prices sit well below the coast. That lowers the stakes in dollars, but it also means a small drop in value can erase a small margin.
Kamloops benchmarks by month and type
The Association of Interior REALTORS’ September 2026 single-family benchmark for Kamloops was $659,100, down about $25,000 from the summer months and the third monthly drop in a row, according to CFJC. In its October 2026 release the townhome benchmark was $511,900, up 1.6% on the year, and the condo benchmark was $359,200, down 2.5%. The same release said the single-family benchmark fell by less than 1%, and it gave no exact October figure, so we use September.
Statistics Canada’s 2021 count for Kamloops was 97,902 residents, up 8.4% from 90,280. Homes sold in September numbered 189, against 222 in September 2025.
Equity and room are different numbers in Kamloops
The line the Financial Consumer Agency of Canada draws is 80% of appraised value, minus what you owe on your mortgage. A single-family owner with a $380,000 first mortgage has $147,280 of room. A condo owner with a $230,000 first mortgage has $57,360, and after the fees in the second example the cash that reaches the debts is $42,600. The calculator lets you subtract fees before you decide how much to borrow. Our consolidation page explains when this arithmetic fails.
Deferring property tax and other provincial options
If you are 55 or older, a surviving spouse or a person with disabilities, BC’s property tax deferment program may be open to you. The province pays your property tax after the due date and registers a lien against your home. Interest applies, compounding from 2026. It covers only the tax bill, not other debts, so it is a narrower tool than a loan. If you are already behind on tax, read our page on property tax arrears.
Acreage, lots and what a lender counts
Kamloops and the surrounding area include larger lots and rural properties. A benchmark describes a typical house, and acreage or lakefront property prices differently. A lender may value land or outbuildings separately. Our page on rural property second mortgages covers what they ask, and the bad credit page covers pricing when credit is weak.
Fees, tax and the rate backdrop
A second mortgage in Kamloops carries interest, a lender fee, often a broker fee, legal costs and an appraisal. The BC property transfer tax is charged on purchases, and we found no line for a loan on a home you keep. If you fall behind, Legal Aid BC says a BC lender cannot sell your home without your consent or a court order, and the court usually sets a redemption period of six months. We found no Kamloops-specific arrears or renewal figure, so we give none.
What to ask before you borrow in Kamloops
A lender in Kamloops will want your mortgage statement, your property tax notice and a clear explanation of how the loan will be repaid. If your income is seasonal or irregular, bring two years of records so a lender can see the pattern. If you own a condo, ask for the strata fee statement and recent minutes.
Ask each lender for every cost in writing, add them up for the first year and compare the totals. With smaller loan amounts, flat fees take a larger share, and a $1,500 legal bill is a bigger part of a $45,000 loan than of a $150,000 one, as the second example above shows.
Townhomes and condos in the same city
The Kamloops townhome benchmark of $511,900 rose 1.6% over the year, while the condo benchmark of $359,200 fell 2.5%. At 80%, the townhome ceiling is $409,520 and the condo ceiling is $287,360, a gap of $122,160. If you own the cheaper type and the value is still sliding, build a bigger margin into the plan than the arithmetic alone suggests.
Getting a second read on a Kamloops plan
A licensed mortgage professional in British Columbia can price a bank, a credit union and private lenders against your plan, and tell you how big a drop in value it can absorb. The British Columbia page covers provincial rules and costs. To have someone go over your Kamloops numbers, see your options.
A Kamloops single-family home at the September 2026 benchmark
The $659,100 value is the Association of Interior REALTORS' September 2026 Kamloops single-family benchmark, used as a stand-in for an appraisal. The $380,000 first mortgage and $50,000 loan are made up. The 80% ceiling is the Financial Consumer Agency of Canada's figure for a second mortgage.
- Home value used
- $659,100
- Owed on the first mortgage
- $380,000
- Combined loan-to-value with a $50,000 loan
- 65.2%
- 80% of the home value
- $527,280
- Room left after the new loan
- $97,280
- Room under an 80% ceiling before the loan
- $147,280
$430,000 divided by $659,100
$147,280 minus $50,000
A Kamloops condo used to clear $45,000 of debt
The $359,200 value is the Association of Interior REALTORS' October 2026 Kamloops condo benchmark, used as a stand-in for an appraisal. The $230,000 first mortgage, $45,000 loan, 2% lender fee and $1,500 legal costs are made up.
- Room under an 80% ceiling before the loan
- $57,360
- Combined loan-to-value with a $45,000 loan
- 76.6%
- Lender fee
- $900
- Legal costs
- $1,500
- Room left after the new loan
- $12,360
- Cash left to pay the debts
- $42,600
$287,360 minus $230,000
$275,000 divided by $359,200
2% of $45,000
$57,360 minus $45,000
Questions people ask
Which month's Kamloops price should I use for a single-family home?
The latest single-family benchmark we could open was September 2026 at $659,100, reported by CFJC from Association of Interior REALTORS data, the third straight monthly drop. The Association's October release gave townhome and condo benchmarks but we found no exact single-family figure.
How much equity do Kamloops condos hold for a second mortgage?
Often not much. The October 2026 condo benchmark was $359,200, down 2.5% on the year, so 80% is $287,360. A $230,000 first mortgage leaves $57,360 before any loan, and fees come out of what is borrowed.
Instead of borrowing, can I defer my Kamloops property tax?
If you are 55 or older, a surviving spouse or a person with disabilities, you may qualify for BC's deferment program. The province pays the tax and registers a lien, and interest is charged. It covers only the tax bill, not other debts.
Might lenders treat homes on larger lots or acreage near Kamloops differently?
They can. A lender may exclude or discount land, outbuildings and lakefront or acreage value, because those add value differently from a standard house. Ask what a lender will count, and do not assume the benchmark fits your property.
Sources
- CFJC Today: September real estate sales slow in Kamloops, October 5, 2026 (as reported by CFJC Today, citing the Association of Interior REALTORS), 2026-10-05
- Infonews: Sales and prices down in Central Okanagan, Kamloops real estate markets, November 5, 2026 (as reported by Infonews, citing the Association of Interior REALTORS), 2026-11-05
- Statistics Canada: Census Profile, 2021 Census of Population, Kamloops, City (CY) [Census subdivision]
- Government of BC: Property tax deferment program
- Legal Aid BC: Can't Pay Your Mortgage?
- Financial Consumer Agency of Canada: Borrowing against your home equity