
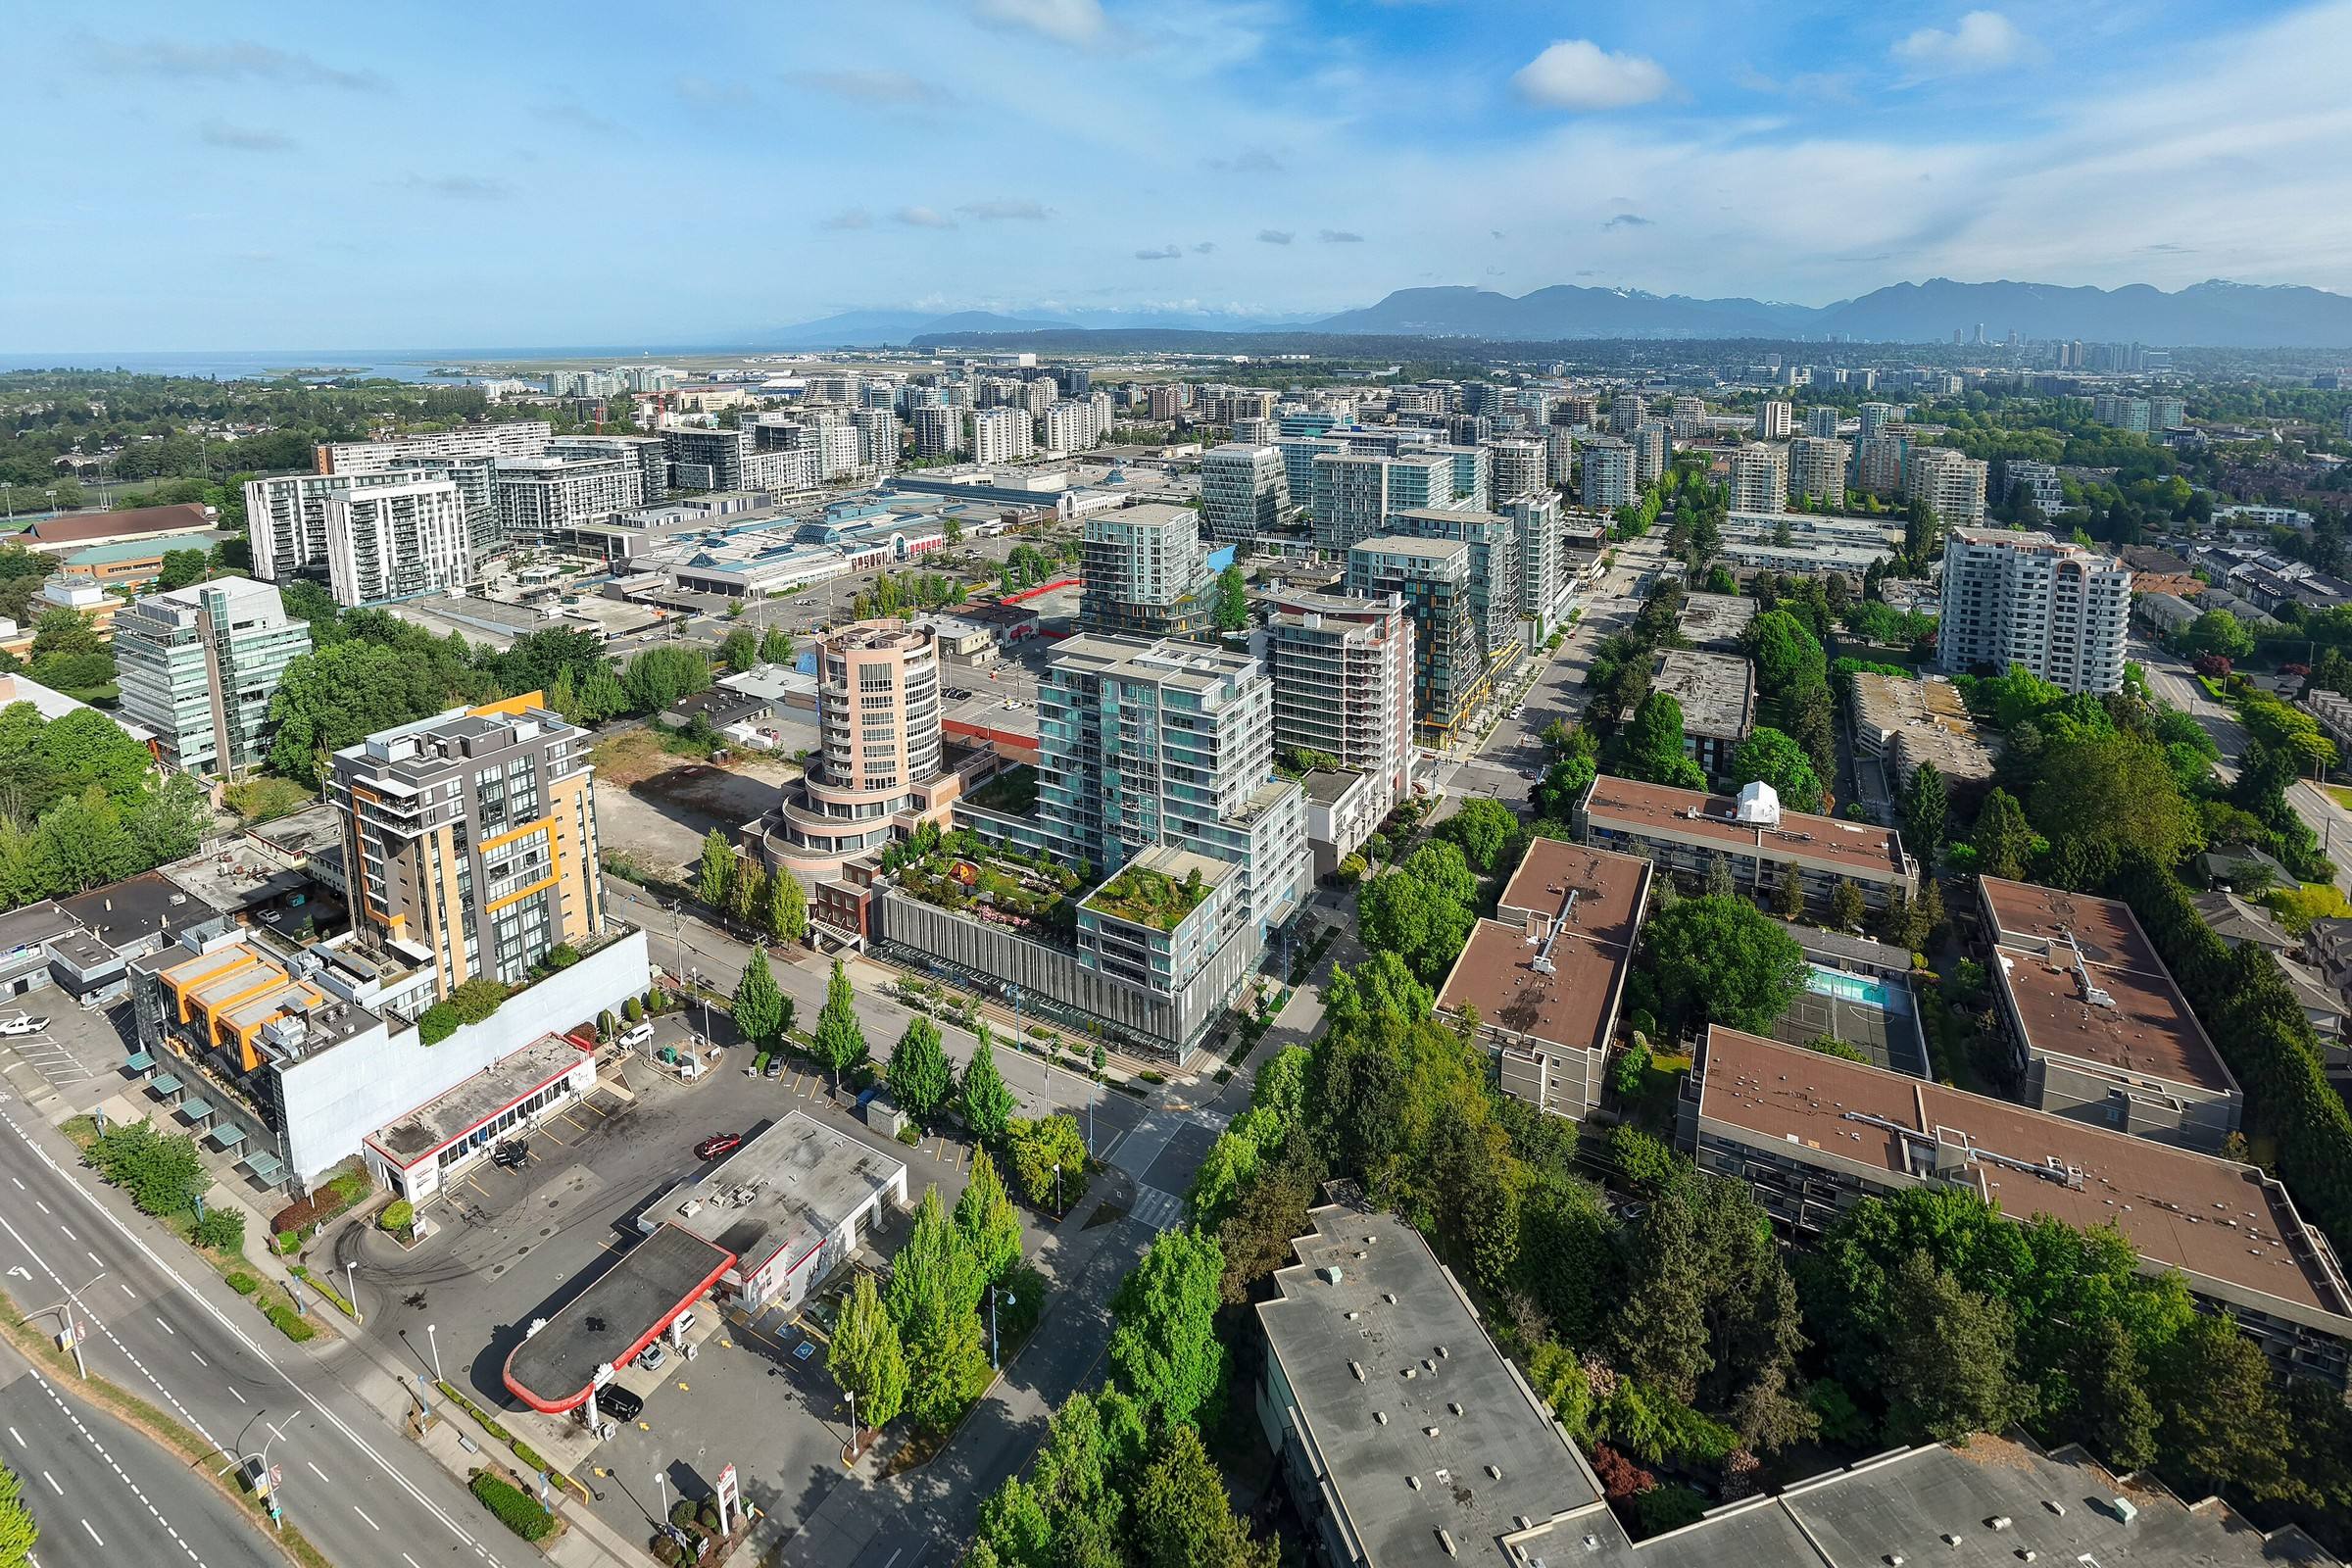

- Benchmark price, all home types, Richmond
- $998,300As of October 2026.Source
- Benchmark detached home, Richmond
- $1,833,100As of October 2026.Source
- One-year change in the Richmond all-home benchmark
- down 8.3%As of October 2026.Source
- Population of the City of Richmond
- 209,937As of 2021 Census.Source
On this page
Richmond is a city of detached houses, townhomes and condos near the airport and the river, and in the last year it has been one of the weaker price performers in the Greater Vancouver REALTORS area.
Richmond in October: the benchmarks
The all-home benchmark in Richmond was $998,300 in October 2026, down 1.7% from September and 8.3% from October 2025. The detached benchmark was $1,833,100. Greater Vancouver REALTORS describes its benchmark as the estimated sale price of a typical property in each market, so your own home may sit above or below it.
Richmond counted 209,937 residents in 2021, 5.9% more than the 198,309 of 2016. Metro-wide, GVR counted 2,024 sales in October 2026, 22.5% below the ten-year seasonal average, which means fewer sales to anchor an appraiser’s comparison.
Why a $1.8 million house can leave very little room
The first example above is the point of this page. A detached owner with a $1,200,000 first mortgage has $633,100 of equity at the benchmark price, but under the Financial Consumer Agency of Canada’s 80% rule the room is $266,480. Borrow $250,000 and $16,480 remains. The second example shows the same city at the all-home benchmark with a smaller loan and a healthy margin.
When you plan a loan, add the fees to the amount before you test the ceiling. The calculator does this. If the plan is to buy another property, our page on equity for a down payment explains how lenders count the new debt, and bridge loans covers the gap between a purchase and a sale.
Property transfer tax on a Richmond purchase
BC charges property transfer tax at 1% on the first $200,000 of fair market value, 2% from $200,000 to $2,000,000 and 3% above that, with a further 2% on residential value over $3,000,000. At the Richmond detached benchmark of $1,833,100 that comes to $2,000 plus $32,662, or $34,662. The tax is calculated on value, not on what you owe, and the government page does not list mortgages as taxable. It matters here for owners who sell and buy again, and for anyone using home equity toward a purchase.
For a loan on a home you keep, your costs are the lender fee, broker fee, legal costs and an appraisal. If the purpose is an investment, read about borrowing against a rental property, since lenders look harder at those files.
Line of credit or second mortgage
Richmond owners with strong income often try their bank first. A home equity line from a bank is revolving, usually costs less and has no fixed term, but the bank sets the tests. A second mortgage has a term, fees and a payoff date. Our comparison HELOC or second mortgage sets the two side by side. The honest answer for many Richmond owners is to ask the bank first and use a second mortgage only if the bank says no.
What we did not find
We did not find a Richmond-specific arrears or mortgage renewal figure from a source we could open, so none is given. The figure that matters most is the price drop, because every lender counts 80% of today’s value.
House, townhome or apartment in Richmond
The detached benchmark of $1,833,100 was down 11.1% from October 2025, a bigger fall than the all-home figure. The townhome benchmark was $1,009,300, down 4.5%, and the apartment benchmark was $625,700, down 8.8%.
That order matters for borrowers. A house owner has the most room in dollars and the sharpest fall in value, while an apartment owner has a smaller ceiling and a smaller cushion. If you own a Richmond detached house and bought or refinanced in the last two years, ask how your lender’s appraisal compares with what you paid.
Selling to repay is a risk to price in
GVR counted 4,805 new listings across Metro Vancouver in October 2026, down 11.6%, and 15,688 active listings, down 4.3%. Richmond owners who plan to repay a second mortgage by selling the house are selling into a market with plenty of choice for buyers. Ask any lender what the loan costs if the term ends before the sale closes, and whether an extension is possible and at what fee.
Choosing a licensed professional in Richmond
A licensed mortgage professional in British Columbia can test your plan against the appraisal and compare lenders. The British Columbia page explains the provincial rules and costs. Should you want someone to run your Richmond figures, start with your options.
A Richmond detached home near the October 2026 benchmark, large first mortgage
The $1,833,100 value is GVR's October 2026 benchmark for a detached home in Richmond, used as a stand-in for an appraisal. The $1,200,000 first mortgage and $250,000 new loan are made up. The 80% ceiling is the Financial Consumer Agency of Canada's figure for a second mortgage.
- Home value used
- $1,833,100
- Owed on the first mortgage
- $1,200,000
- Combined loan-to-value with a $250,000 loan
- 79.1%
- 80% of the home value
- $1,466,480
- Room left after the new loan
- $16,480
- Room under an 80% ceiling before the loan
- $266,480
$1,450,000 divided by $1,833,100
$266,480 minus $250,000
A Richmond home at the October 2026 all-home benchmark, with a smaller loan
The $998,300 value is GVR's October 2026 all-home benchmark for Richmond, used as a stand-in for an appraisal. The $600,000 first mortgage and $80,000 loan are made up.
- Home value used
- $998,300
- Equity before the new loan
- $398,300
- Combined loan-to-value with an $80,000 loan
- 68.1%
- 80% of the home value
- $798,640
- Room left after the new loan
- $118,640
- Room under an 80% ceiling before the loan
- $198,640
$998,300 minus $600,000
$680,000 divided by $998,300
$198,640 minus $80,000
Questions people ask
How far did Richmond prices fall in 2026?
Greater Vancouver REALTORS reported the Richmond all-home benchmark at $998,300 in October 2026, down 8.3% from October 2025 and 1.7% from September. That is one of the larger one-year drops among the areas it tracks, and it directly reduces equity lenders can count.
Would I owe property transfer tax if I sold my Richmond house and bought another?
On the purchase, yes. At the $1,833,100 detached benchmark the schedule works out to $34,662: 1% on the first $200,000 and 2% on the remaining $1,633,100. A loan against a home you keep is not a purchase. Confirm figures with your lawyer or notary.
Could my Richmond equity fund a down payment on another property?
It can, but the lender will count the new debt against your income and the home it is secured on. If the second property is a rental, a lender may treat it differently again. Run the 80% ceiling on your current home first.
HELOC or second mortgage: which is easier to carry in Richmond?
It depends on the terms offered, not the city. A bank line of credit usually carries lower costs but needs you to meet the bank's tests. A second mortgage has fees and a fixed term. Compare yearly cost and what happens at the end of the term.