
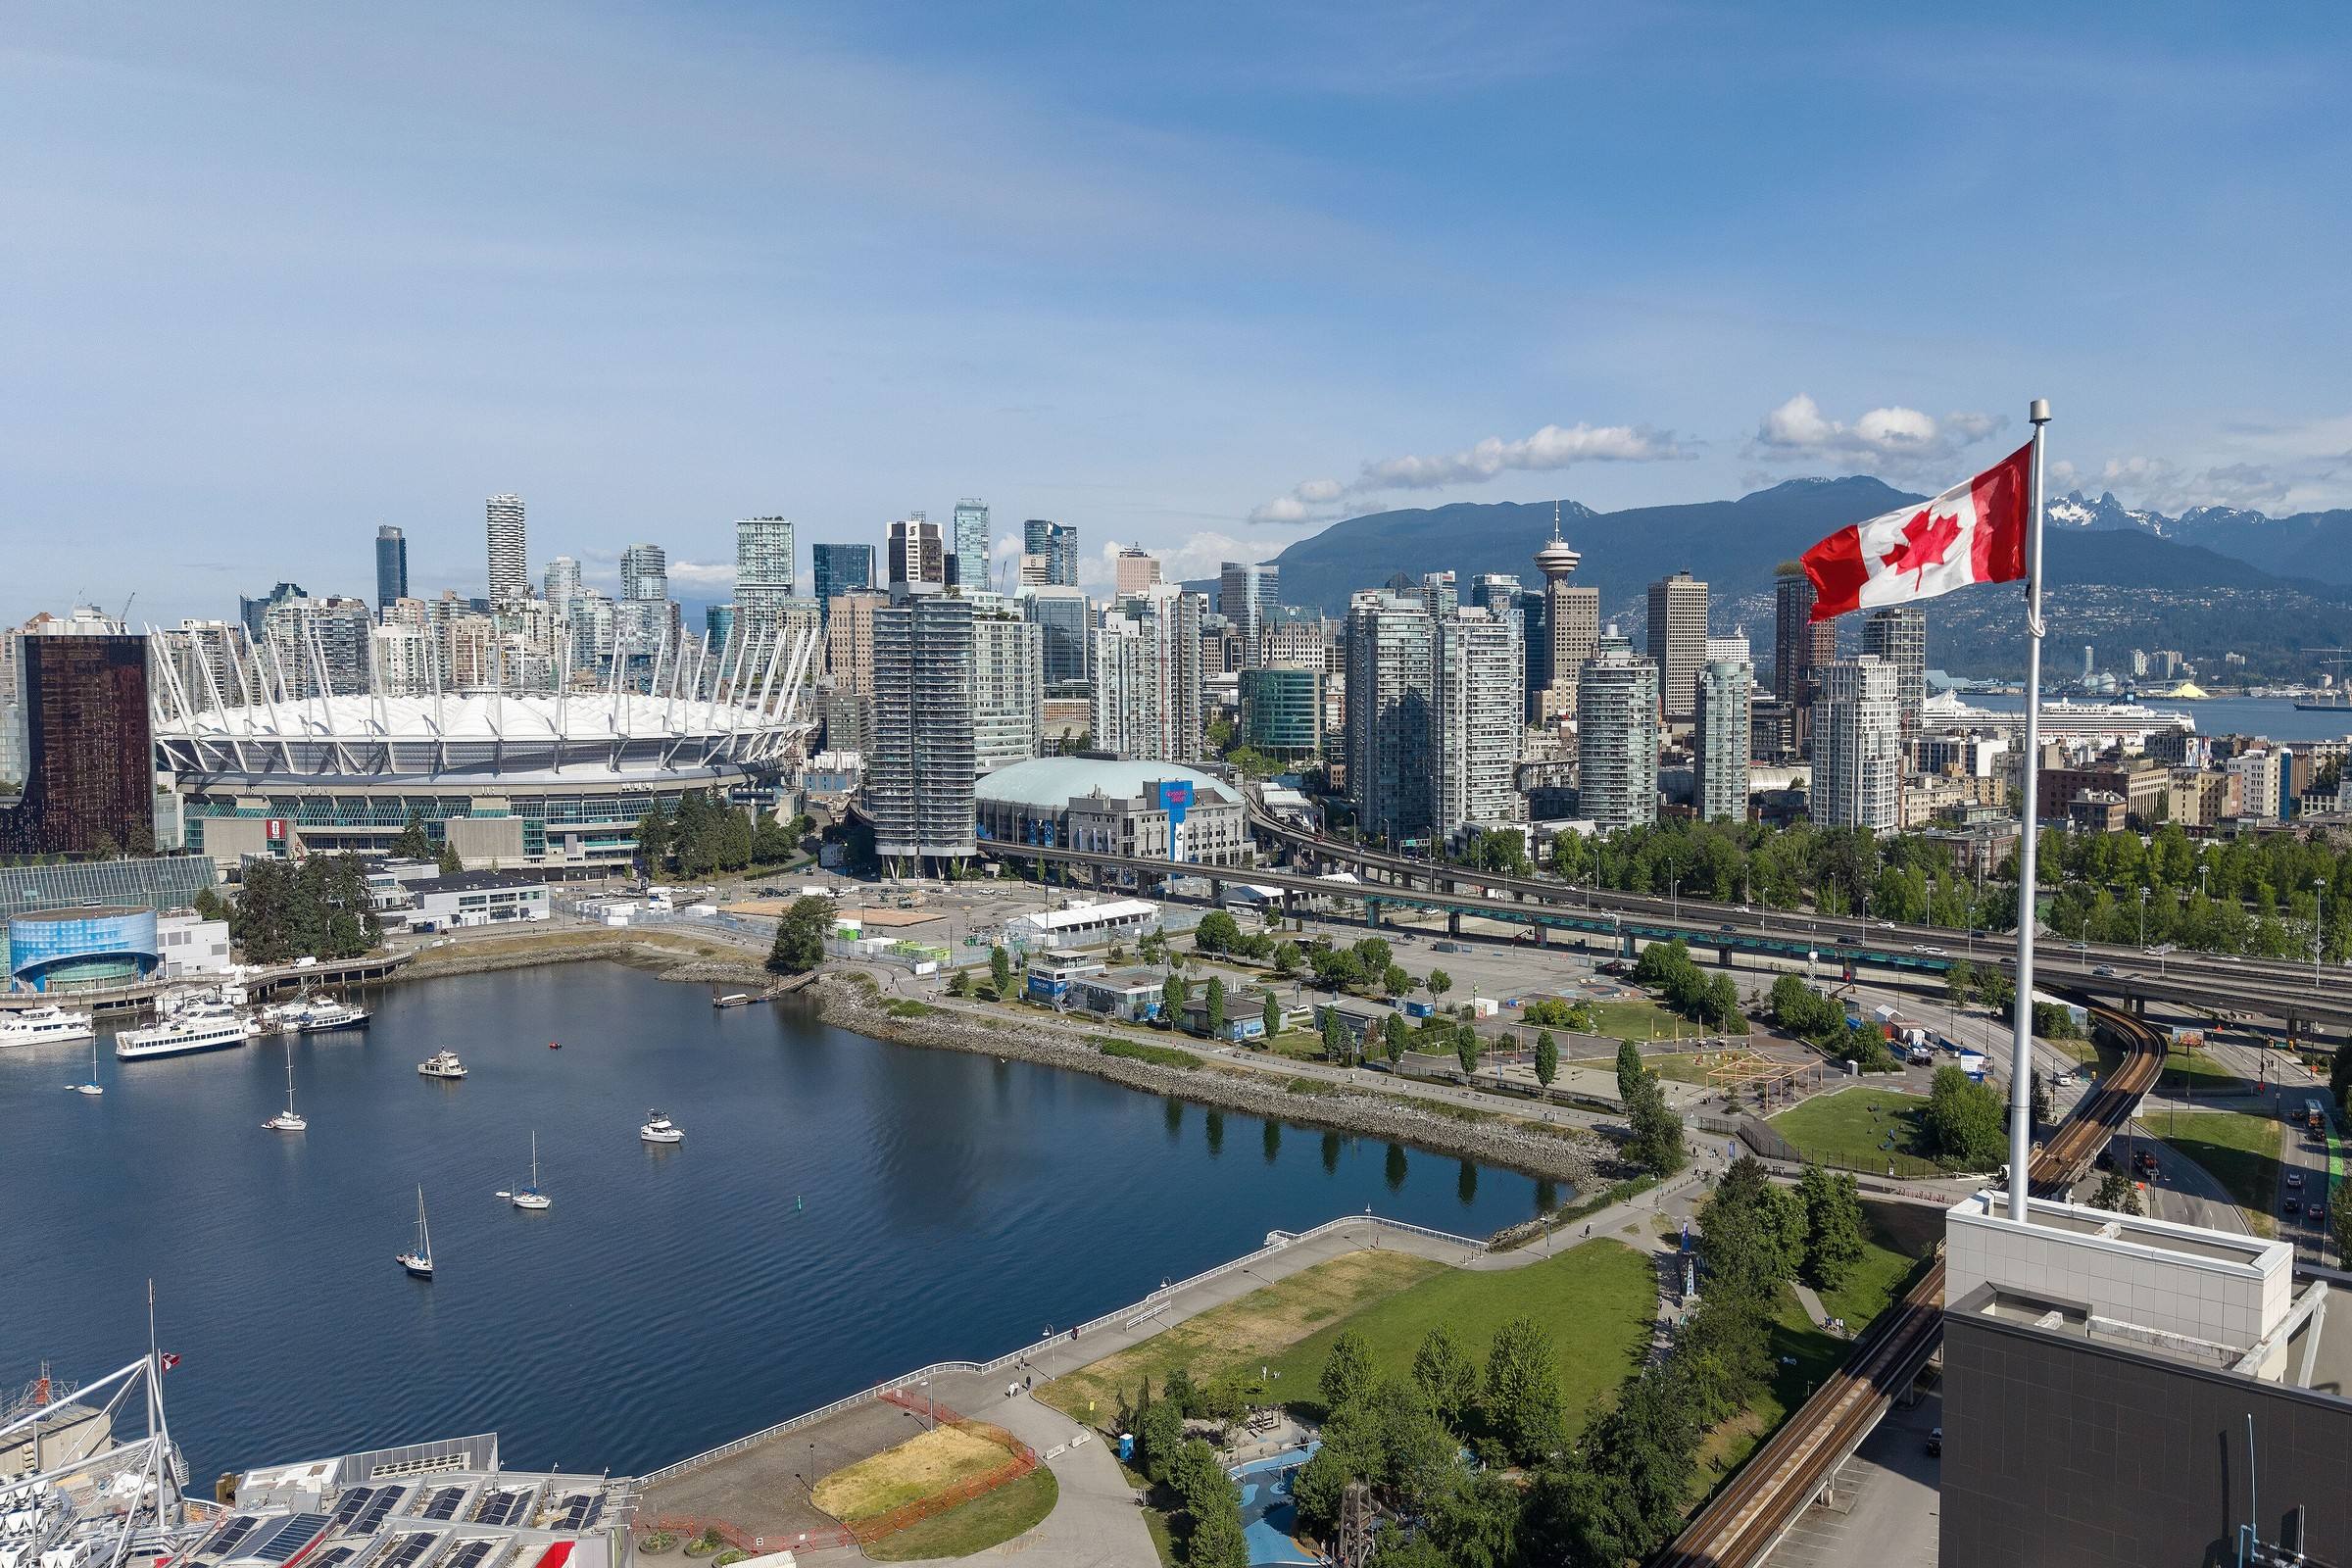

- Benchmark detached home, Vancouver West
- $2,899,700As of October 2026.Source
- Benchmark price, all home types, Vancouver East
- $1,121,600As of October 2026.Source
- Benchmark price, all home types, Vancouver West
- $1,196,600As of October 2026.Source
- Population of the City of Vancouver
- 662,248As of 2021 Census.Source
- Vancouver area mortgages 90 or more days behind (Equifax, CMHC)
- 0.24%As of second quarter of 2026.Source
On this page
Vancouver is two housing markets inside one city limit. A detached house on the west side and an older home in the east end can be a million dollars apart, and the second mortgage conversation looks different in each.
October’s Vancouver prices and your equity
Greater Vancouver REALTORS publishes a benchmark price, which is an estimate for a typical property in each area. In October 2026 it was $1,196,600 for all home types in Vancouver West and $1,121,600 in Vancouver East, down 4.5% and 4.4% from a year earlier. For detached homes alone the benchmark in Vancouver West was $2,899,700.
Across Metro Vancouver there were 2,024 sales that month and 15,688 homes listed, which GVR says is 24% above the ten-year seasonal average. Its sales-to-active-listings ratio was 13.4%. GVR notes that prices tend to come under pressure when that ratio stays below 12% for a long stretch, so a further price drop is a real possibility for owners who plan to borrow against today’s value. In the 2021 Census Vancouver counted 662,248 people, 4.9% above 2016.
Why Vancouver equity can feel bigger than it is
A Vancouver owner can feel rich on paper and still find the borrowing room smaller than expected. The Financial Consumer Agency of Canada draws the line at 80% of the appraised value less your mortgage balance. The two examples above show the spread. The west-side detached owner has $919,760 of room. The east-side owner with a $700,000 mortgage has $421,600 of equity and $197,280 of room.
If the purpose is clearing debt, the loan must also cover fees. Test it on the calculator, then read how consolidation works and where it backfires.
Strata liens and a transfer tax that rarely applies
Many Vancouver owners live in strata buildings. Legal Aid BC says that if you do not pay strata fees or a special levy, the strata corporation can file a Certificate of Lien against your title, and the lien takes priority even over registered mortgages. A lender who sees that lien may decline, or may ask that it be paid from the new loan. Gather your strata minutes and a statement of account early.
On tax, the province charges property transfer tax on purchases: 1% on the first $200,000, 2% up to $2,000,000 and 3% above that, with a further 2% on residential value over $3,000,000. The Vancouver West detached benchmark sits just under that last line. The government page we read does not list mortgages as taxable, so budget for the lender fee, broker fee, legal costs and appraisal, and have your lawyer confirm.
Rates and arrears across Metro Vancouver
GVR’s chief economist described October 2026 as a month with a somewhat surprising Bank of Canada rate hike, and said buyers who have watched prices drift lower have seen those gains eroded by higher borrowing costs. For existing owners, CMHC’s Fall 2026 report puts the share of Vancouver area mortgages 90 or more days behind at 0.24% in the second quarter of 2026, up from 0.17% a year before. CMHC says its British Columbia figure and its Vancouver figure come from different data sources, so we do not compare them.
Those numbers are low. They matter because a lender pricing a second mortgage is watching the same trend. If your first mortgage renews soon, ask the bank for a renewal or a blend and extend first. A second mortgage adds a second payment on top, and our page on renewal payment shock lays out when that trade works.
One city, three property types
The October 2026 GVR tables show how far apart Vancouver’s property types sit. In Vancouver East the detached benchmark was $1,610,700, down 8.3% on the year, while the townhome benchmark was $1,055,800, up 0.4%, and the apartment benchmark was $635,100, down 3.9%. In Vancouver West the townhome benchmark was $1,285,000 and the apartment benchmark $751,400, down 3.8%. Detached homes in Vancouver West fell 9.0%.
Across Metro Vancouver, GVR counted 643 detached sales and 892 apartment sales in October, with a sales-to-active-listings ratio of 11.6% for detached homes and 13.5% for apartments. A lower ratio means more sellers per buyer. For a borrower, the practical point is that a detached owner in a softer segment should expect an appraiser to be cautious, and should not assume the benchmark carries over to a specific street.
A licensed professional and the strata paperwork
Take your first mortgage, strata position and purpose to a licensed mortgage professional in British Columbia, who can set banks, credit unions and private lenders next to each other. The British Columbia page covers licensing and costs, and the home equity loan page explains the product itself. If you want a view of your own Vancouver figures, weigh up your options.
A Vancouver West detached home at the October 2026 benchmark
The $2,899,700 value is GVR's October 2026 benchmark for a detached home in Vancouver West, used as a stand-in for an appraisal. The $1,400,000 first mortgage and $200,000 new loan are made up. The 80% ceiling is the one the Financial Consumer Agency of Canada gives for a second mortgage.
- Home value used
- $2,899,700
- Owed on the first mortgage
- $1,400,000
- Combined loan-to-value with a $200,000 loan
- 55.2%
- 80% of the home value
- $2,319,760
- Room under an 80% ceiling before the loan
- $919,760
$1,600,000 divided by $2,899,700
A Vancouver East home at the October 2026 benchmark, with a modest loan
The $1,121,600 value is GVR's October 2026 all-home benchmark for Vancouver East, used as a stand-in for an appraisal. The $700,000 first mortgage and $60,000 loan are made up.
- Home value used
- $1,121,600
- Equity before the new loan
- $421,600
- Combined loan-to-value with a $60,000 loan
- 67.8%
- 80% of the home value
- $897,280
- Room left after the new loan
- $137,280
- Room under an 80% ceiling before the loan
- $197,280
$1,121,600 minus $700,000
$760,000 divided by $1,121,600
$197,280 minus $60,000
Questions people ask
Strata unit in Vancouver: does it make a second mortgage harder?
It adds a check. Legal Aid BC notes that a strata corporation can register a lien for unpaid fees or special levies, and that lien ranks ahead of mortgages on the title. A lender will usually ask whether your strata fees and levies are fully paid.
Vancouver West's benchmark price: is it my home's value?
No. GVR's $2,899,700 is a benchmark for a typical detached home in Vancouver West in October 2026. Your lender will order its own appraisal of your house, and a renovated or lane-facing home can come in well above or below the benchmark.
Have Vancouver homeowners fallen behind on mortgages?
CMHC reports that the Vancouver area rate of mortgages 90 or more days behind rose from 0.17% in the second quarter of 2025 to 0.24% in the second quarter of 2026. That is still low, and it is an area figure, not a forecast for your loan.
Does borrowing against my Vancouver home trigger property transfer tax?
The province charges property transfer tax when you buy or gain an interest in property registered at the Land Title Office. The government page we read does not list mortgages. Your lawyer or notary will confirm what applies to the charge being registered.
Sources
- Greater Vancouver REALTORS: Residential Stats Package, October 2026, 2026-11
- Statistics Canada: Census Profile, 2021 Census of Population, Vancouver, City (CY) [Census subdivision]
- CMHC: Residential Mortgage Industry Report, Fall 2026, 2026-11
- Legal Aid BC: Can't Pay Your Mortgage?
- Government of BC: Property transfer tax
- Financial Consumer Agency of Canada: Borrowing against your home equity